European short-term rental supply rose 1.8% in October 2025 as demand softened
AirDNA reported that Europe's available listings reached 3.69 million units in October 2025, while occupancy fell to 54.9% amid flat autumn demand.
Updated 15 October 2026. After a source check by the standards desk, 2 sentences were removed because no source confirmed their specifics. Corrections log.
On November 25, 2025, AirDNA reported that available short-term rental listings in Europe reached 3.69 million units in October 2025, representing a 1.8% year-over-year increase. This growth marked the second consecutive month with supply expansion under 2%, signaling a cooling phase after rapid post-pandemic gains across the continent. At the same time, demand nights slipped by 0.5% year-over-year to 38.2 million, leading to widespread occupancy declines in major European markets.
The slowdown in demand and modest supply growth directly affected occupancy rates, which fell to an average of 54.9% across Europe, representing a 1.8% year-over-year decrease. Average daily rates also softened, declining by 1.5% year-over-year to 120.2 €, which dragged revenue per available rental night down by 3.3% to 66€. Despite these downward pressures, established operators demonstrated pricing resilience, with the Repeat Rent Index posting its ninth consecutive month of positive growth at 4.6% year-over-year.
What the data shows
The performance metrics published by AirDNA for October 2025 revealed a broad softening across the European short-term rental market. Total available listings reached 3.69 million units, which was a 1.8% increase compared to October 2024. This represented a slight acceleration from the low point of 0.6% year-over-year growth recorded in June 2025, which was the slowest expansion rate since May 2022. However, October 2025 was the second consecutive month where supply growth remained below 2%, indicating that the rapid post-pandemic expansion phase had slowed.
Demand nights, which measure short-term rental reservations made for the reporting month of October 2025, fell by 0.5% year-over-year. This decrease resulted in 185,000 fewer demand nights booked compared to October 2024. The decline followed a pattern of flattening demand during the late summer and autumn, with August 2025 showing a minor 0.3% increase and September 2025 registering a 0.9% decrease. This three-month period marked the first time since the pandemic that European demand growth remained below 1% for more than two consecutive months.
With supply continuing to grow faster than demand, occupancy rates suffered. The average occupancy rate across Europe reached 54.9%, which was a 1.8% decline year-over-year. AirDNA reported that occupancy declined in 15 of the top 20 European countries. Across the top markets, the overall occupancy drop was 1.6% year-over-year, driven by the imbalance between expanding listings and flat booking interest.
Average daily rates (ADR) also felt the downward pressure, falling 1.5% year-over-year to 120.2 €. October 2025 was the seventh month of the year to record negative ADR growth, with only January, February, and May showing positive rate increases. Over the five months leading up to October 2025, the ADR trend remained negative, averaging a 1.7% decline, though October's 1.5% drop was a slight improvement from the 2.1% decrease recorded in September 2025. Consequently, revenue per available rental night (RevPAR) fell by 3.3% year-over-year to 66€.
How it was measured
The figures were compiled and analyzed by AirDNA, a short-term rental data and analytics provider. The performance metrics cover short-term rental properties active on platforms such as Airbnb and Vrbo during the month of October 2025. AirDNA calculated available listings by tracking the total number of unique units that had at least one day of availability or booked night within the month. Demand nights represent the total number of nights booked for stays that occurred specifically within October 2025.
To measure pricing trends, AirDNA utilized two distinct metrics: Average Daily Rate (ADR) and the Repeat Rent Index (RRI). The ADR is the average rate paid per booked night across all listings, including new properties entering the market. The Repeat Rent Index tracks pricing changes specifically among existing operators who have been active for at least a year, thereby removing the downward pricing pressure often introduced by newly created, lower-priced listings. The economic context was supported by Eurostat data for inflation and unemployment, and GDP projections were sourced from Oxford Economics. Forward-looking pacing data was captured as of November 11, 2025, reflecting bookings made for stays through May 2026.
Regulatory pressures and supply shifts
Although available listings grew in 16 of Europe's top 20 countries, regulatory actions significantly suppressed supply in several key southern destinations. Spain experienced the most severe contraction for the second consecutive month, with available listings falling 8.2% year-over-year. This decline was driven by strict regulatory actions introduced in August 2025, which targeted tens of thousands of short-term rental units. In October 2025 alone, these measures resulted in a 33,000-unit reduction in Spanish supply.
Croatia recorded the second-largest supply decline, with available listings falling 5.9% year-over-year, representing roughly 6,000 fewer listings. Italy also experienced a minor contraction, with supply decreasing by 0.6% year-over-year. In contrast, mature markets in northern and central Europe continued to add listings. France, the largest short-term rental market on the continent, added nearly 18,000 units in October 2025, representing a 1.9% year-over-year increase. The United Kingdom posted a 2.1% supply increase.
Germany led all European nations in absolute supply growth, adding 25,000 listings in October 2025, which was a 7.8% year-over-year rise. Supply growth was also strong in Northern Europe, where Norway saw available listings rise by 12.7% and Denmark recorded a 14% increase. Finland and Sweden posted more moderate supply gains of 2.1% and 5.8% respectively, illustrating the highly uneven pace of supply expansion across the continent.
Stagnating autumn demand and occupancy losses
The 0.5% year-over-year decline in European demand nights during October 2025 reflected a maturing market adjusting to capacity constraints and seasonal normalization. Because short-term rental supply had mostly stabilized after two years of rapid growth, the lack of new inventory in heavily regulated markets like Spain and France limited overall booking availability. Tougher licensing rules and stricter enforcement directly contributed to softer booking activity.
This stagnation in demand, combined with continued supply growth in most countries, led to occupancy losses across 15 of the top 20 European nations. Croatia stood out with a sharp 17% year-over-year decline in demand nights, which contributed to a 5.7% drop in its average occupancy rate. Other major destinations, such as Spain and France, experienced only mild demand softening. The steepest occupancy declines occurred in Croatia, where occupancy fell 5.7%, Norway, where it fell 5.0%, and Sweden, where it fell 4.0%.
Only a small number of countries managed to achieve year-over-year occupancy gains in October 2025. The Czech Republic recorded a 1.8% occupancy increase, Hungary saw a 2.3% gain, and Belgium posted a 1.1% rise. These positive performances were insufficient to offset the broader continental decline, highlighting a clear transition toward a more balanced, slower-growing post-recovery market.
Pricing resilience and the repeat rent index
The contrast between the decline in Average Daily Rate and the strength of the Repeat Rent Index revealed a significant divergence in pricing power. While the overall European ADR fell 1.5% year-over-year to 120.2 €, the RRI rose 4.6% year-over-year. This represented an acceleration from the 4.2% RRI growth recorded in September 2025 and marked the ninth consecutive month of positive RRI growth. The data indicated that established operators with active listings were still able to raise their rates, while the influx of cheaper, newly created listings dragged the broad ADR average down.
ADR performance varied widely by country. The highest year-over-year ADR growth among the top 20 European nations was recorded in Sweden, where rates rose 4.2%, followed by the Czech Republic with a 3.9% increase and Poland with a 3.6% rise. Conversely, the most significant ADR declines occurred in France, where rates fell 7.9%, Finland, with a 4.8% drop, and Greece, which saw a 3.6% decline.
France's 7.9% drop in ADR occurred despite a 3.7% increase in its Repeat Rent Index. AirDNA attributed this discrepancy to a normalization of demand following the Paris 2024 Olympics. The temporary price spikes enjoyed by hosts in Paris, Marseille, and Lyon during the Olympics corrected downward in October 2025 to more sustainable levels. This correction was amplified by a 1.9% rise in French supply, which consisted primarily of lower-priced listings that shifted the overall market mix downward.
Forward pacing and Olympic demand in Italy
Looking ahead into early 2026, European short-term rental demand pacing showed signs of continued easing. As of November 11, 2025, booked demand nights for stays through May 2026 were roughly 2% lower than the level recorded at the same point in the previous year. This slowdown was most pronounced during the spring shoulder months of March and April 2026, where booked nights were down 5% to 7% year-over-year. However, December 2025 bookings were up 3% year-over-year, indicating healthy holiday travel demand, while May 2026 bookings tracked flat compared to the previous year.
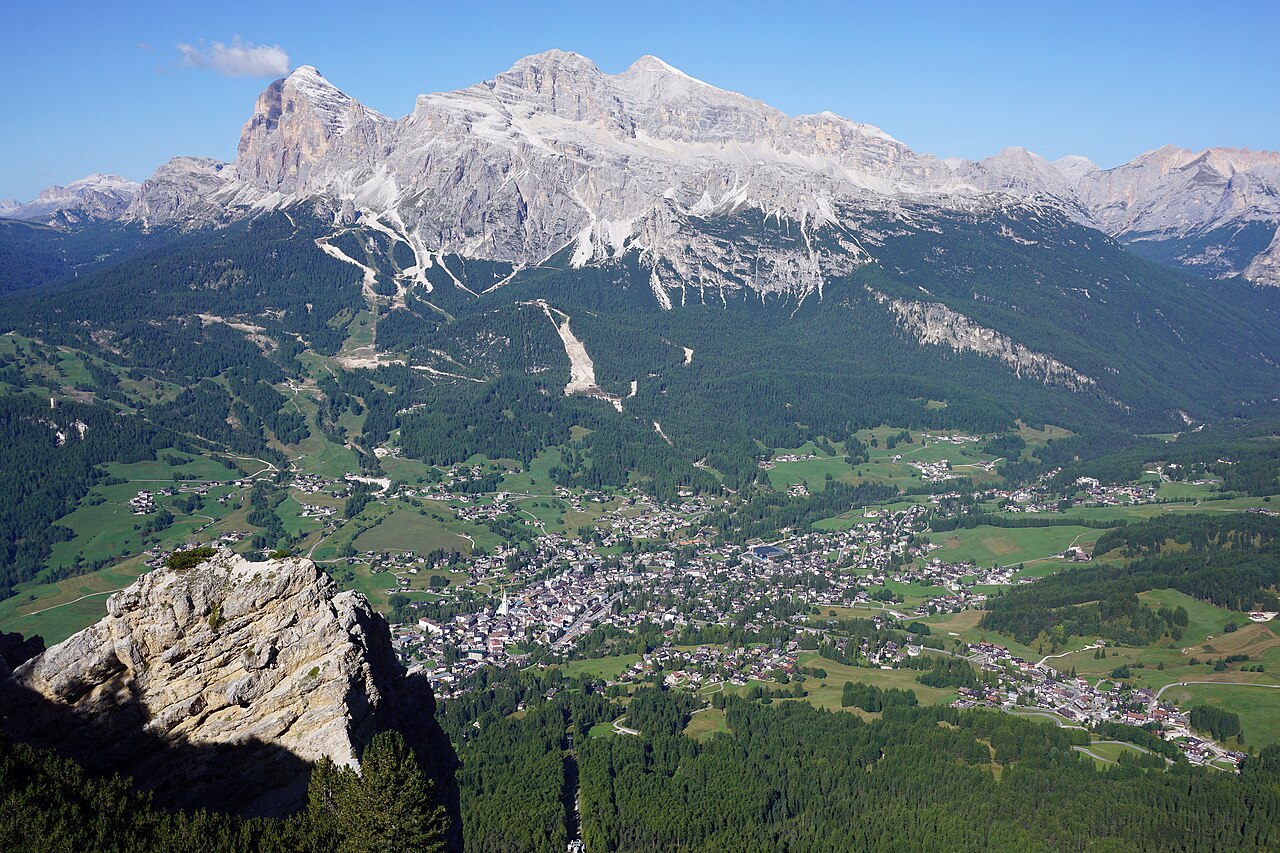
Northern Italy emerged as a major exception to this cooling trend, driven by the November 25, 2025 report on the Milano-Cortina 2026 Winter Olympics. Booking demand in Milan for February 2026 more than doubled compared to February 2025, reflecting the city's role as the primary gateway and host for the Games. This demand surge spread to nearby Alpine destinations and host regions, with Verona recording a 94% year-over-year increase in bookings and Antholz-Anterselva posting a 143% increase.
Because of this tightening supply, Livigno's occupancy rate actually rose by 10% year-over-year, demonstrating that local demand remained strong despite the lower volume of total bookings.
What to take from it
Operators and investors must adapt to a mature, capacity-constrained European market where regulatory compliance and local event dynamics dictate performance.
- Monitor the gap between local average daily rates and the Repeat Rent Index to determine whether pricing pressure in a market is driven by cheap new listings or a genuine loss of pricing power among established hosts.
- Track local regulatory actions closely, as sudden enforcement measures—like those in Spain that cut 33,000 units in a single month—can rapidly alter the competitive landscape and drive up occupancy for remaining legal listings.
- Anticipate post-event corrections in markets that host major global events, preparing for average daily rates to normalize downward in the year following an event like the Olympics.
- Evaluate forward pacing data with caution, accounting for shorter booking windows that can make off-peak months appear weaker in early data than they will ultimately turn out to be.
Figures checked by the standards desk (Paul Ostrowski): every figure in this story was matched to the source material listed below before publication. The desk's review raised 1 point, corrected before publication.
Sources
- AirDNA - published November 25, 2025.
Part of the Booked News record for November 2025. The desk filed this story on October 9, 2026 from a source published in the month it covers, under the same figure rule as the daily news.
Re-checked by the standards desk on 15 October 2026 against the original sources and a public-source lookup: 2 sentences were removed because no source confirmed their specifics.
Report an error in this story · Corrections policy and log
Related stories
European short-term rental rates rose 8.2% in July 2026 as occupancy steadied
U.S. short-term rental RevPAR rose 4.5% in June 2026
U.S. short-term rental occupancy rose to 57.2% in May 2026
European short-term rental rates rose 8.2% in March 2026 as supply growth accelerated
Read the desk every morning.
Leave your address for the Booked News briefing: the day's figures on rates, occupancy, demand, fees, supply and returns, each with its source, in one short email.
Comments