The top rental market in the median U.S. state had a 10.91% modeled gross yield
An analysis of 50 states showed that high mortgage rates and management fees left nearly half of the top-performing municipal markets unprofitable.
On September 8, 2026, an analysis of BNBCalc data showed that the top short-term rental market in the median U.S. state produced a modeled gross yield of 10.91%. The study evaluated the highest-performing city in each of the 50 states to determine how much gross revenue properties generated relative to their purchase prices.
The findings highlighted a significant gap between top-line gross yields and the actual net returns received by investors. While gross yields in top-performing markets reached as high as 15.35% in Sandusky, Ohio, the analysis demonstrated that conventional financing costs, operating expenses, and property management fees could easily eliminate positive cash flow, leaving many of the top-ranked municipal markets unprofitable under typical purchase terms.
What the data shows
The data analyzed by BNBCalc revealed that the highest-performing short-term rental markets by gross yield were often located in unglamorous, mid-sized cities rather than popular vacation destinations. According to the report, Sandusky, Ohio, led the nationwide list with a modeled gross yield of 15.35%. This yield was calculated across 181 analyzed properties with a median home value of $145,150. The report noted that the local tourism market was heavily driven by the Cedar Point amusement park, and with 48% of listings managed by independent hosts, the market had not yet fully professionalized.
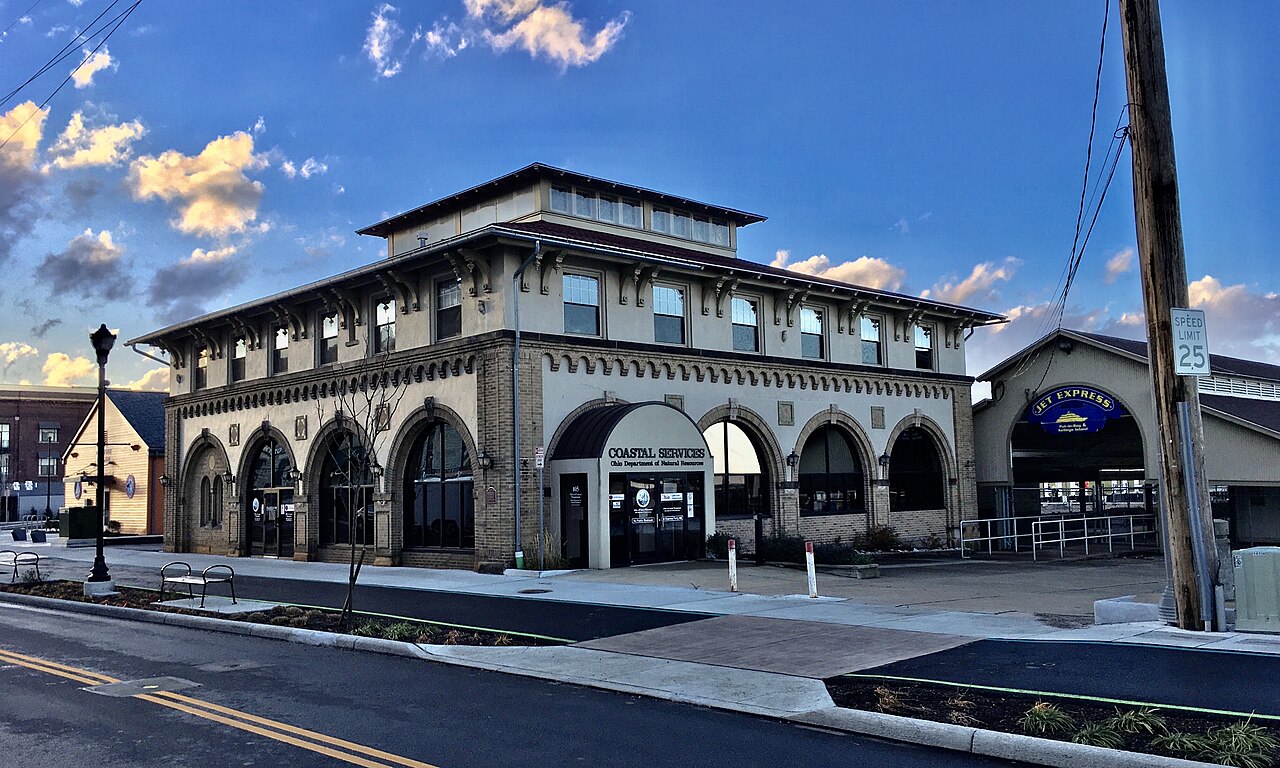
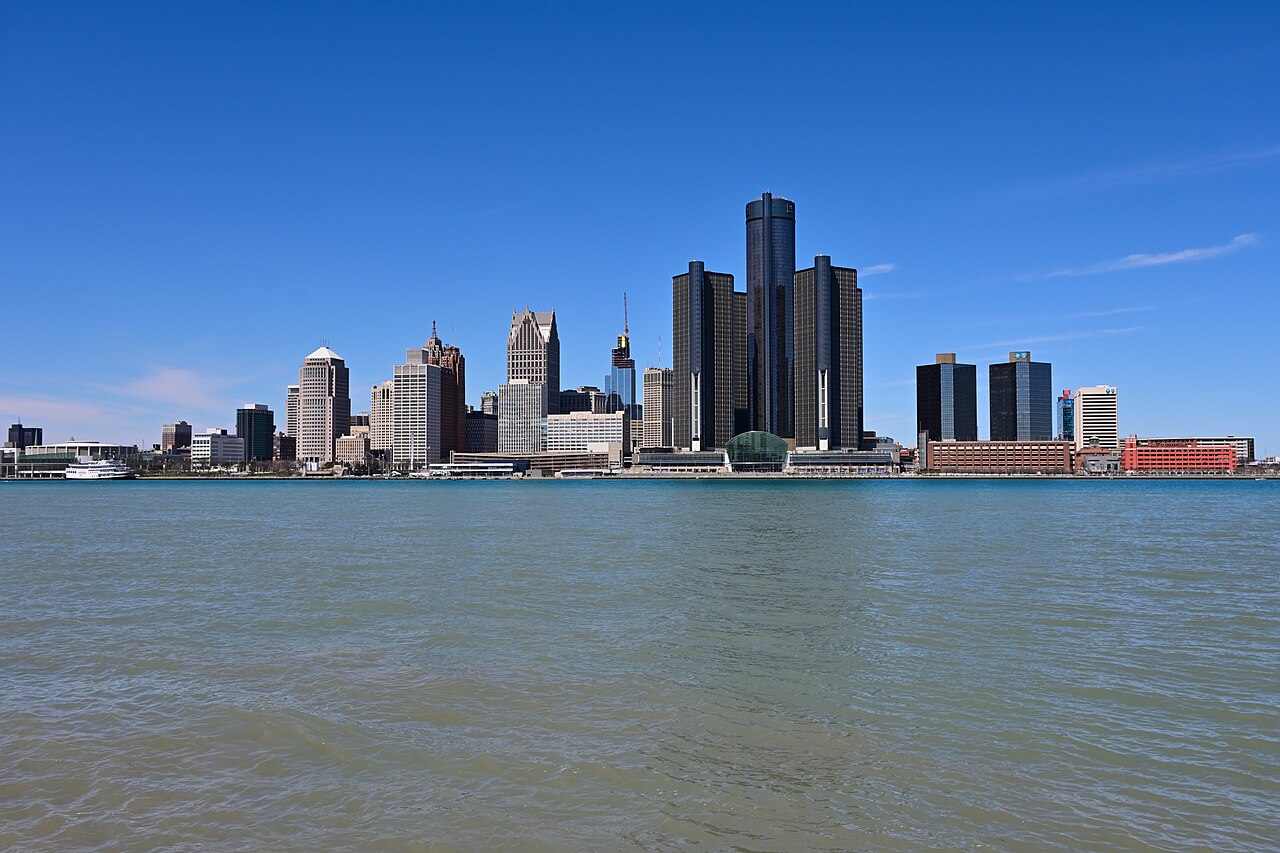
Other high-performing markets included Detroit, Michigan, which produced a 15.1% gross yield across a deeper sample size of 506 properties, with a median home value of $137,024. Because of the size of the city, the report cautioned that this citywide figure averaged streets that performed well with streets that did not, requiring investors to perform address-level research. Kapolei, Hawaii, followed closely with a 15.06% gross yield across 337 properties. While Kapolei had a high median home value of $597,065, it generated $109,736 in annual revenue, which was by far the largest revenue figure recorded in the dataset.
In Abilene, Texas, properties achieved a 15.05% gross yield across 315 properties with a median home value of $194,996. Unlike seasonal coastal or mountain destinations, Abilene featured 58% independent hosts and experienced steady, year-round demand despite lacking traditional tourist draws like beaches or theme parks.
At the opposite end of the spectrum, Lewes, Delaware, ranked last on the list of state winners, producing a gross yield of just 5.43% across 212 properties with a median home value of $540,439. The report noted that Delaware’s best available market yielded under 6% gross, a level that would not survive typical mortgage costs. The broader pattern showed that highly desired mountain and coastal markets sat near the bottom of the yield table, as buyers paid a premium for the address itself, which did not translate into a proportional increase in booked nights.
How it was measured
The figures were produced by BNBCalc, a short-term rental analytics platform that covered more than 10 million listings across 2,400 global markets, including 487 U.S. metro markets. To compile the state rankings, BNBCalc analyzed 462 cities across all 50 states, requiring that each city have a sample size of at least 50 real properties to ensure data reliability.
Modeled gross yield was defined as annual short-term rental revenue divided by the city’s median home value for the same bedroom count. To prevent unusual or outlier properties from skewing the municipal averages, the analysis used the median performance result and required a sufficient volume of listings and independent hosts. The analysis ranked the top city in each state by revenue per dollar of purchase price, removing any markets where BNBCalc’s internal quality review flagged data inconsistencies. Notably, Kansas City appeared twice in the final dataset—once on the Kansas side of the state line and once on the Missouri side—with the Kansas side showing a stronger yield.
The financial friction of mortgages and management
The report featured a detailed financial model illustrating how quickly a strong gross yield could evaporate under conventional purchasing and operating assumptions. To demonstrate this, the author applied typical financing terms to the median winning property from the dataset, which had a median value of $251,338 and produced $27,671 in annual revenue, representing a gross yield of 10.91%.
Under the model’s assumptions, an investor making a 20% down payment would contribute $50,267 of their own capital. Financing the remaining balance with a 30-year mortgage at an interest rate of 7% resulted in annual debt service of $16,052. Operating expenses, estimated at 37.5% of gross revenue to cover cleaning, supplies, utilities, insurance, property taxes, and maintenance repairs, consumed another $10,376. After subtracting debt service and operating expenses, the investor cleared about $1,241 in annual net cash flow. This represented a cash-on-cash return of just 2.5% on the initial $50,267 investment.
The financial outlook deteriorated further if the investor hired a professional property manager. Assuming a standard management fee of roughly 20% of gross revenue, which amounted to $5,534, the property’s positive cash flow was entirely erased, resulting in an annual net loss of about $4,292.
To break even on debt service and operating costs before generating any profit, a property purchased under these conventional assumptions required a gross yield of roughly 10.5%. Out of the 50 top-performing state cities identified in the report, 24 failed to clear this 10.5% break-even threshold. This meant that approximately half of the highest-yielding markets in each state failed to break even on a conventional purchase at the prevailing interest rates.
Regulatory boundaries and zoning risks
A critical limitation of gross yield rankings is their inability to account for local short-term rental ordinances and zoning laws. The report emphasized that a highly favorable yield could exist in a municipality that had heavily restricted or outlawed short-term rentals.
Kapolei, Hawaii, served as the primary example of this regulatory dynamic. While the citywide gross yield was a strong 15.06%, this performance was entirely dependent on local zoning boundaries. The city of Honolulu permitted short-term rentals in resort-zoned areas and select apartment districts, but imposed strict minimum-stay requirements on residential properties throughout the rest of Oahu. The municipality had spent years in court litigating whether the minimum stay for residential rentals should be 30 days or 90 days. Because the Ko Olina neighborhood, which sits within Kapolei, was a designated resort area, short-term rentals were permitted, making the 15.06% yield real but highly localized. A citywide average could not identify which side of the zoning line a specific address occupied.
The report noted that other high-performing markets, including Atlantic City, Baltimore, Detroit, and Myrtle Beach, were located in municipalities that had been actively rewriting their short-term rental regulations, creating ongoing compliance risks for investors.
Tax mitigation and analytical tools
To help investors assess these financial and regulatory challenges, the report detailed how BNBCalc’s analytical tools, such as its AI Agent, could be used to evaluate specific properties. The platform allowed users to enter a specific address to generate revenue projections, average daily rates, occupancy metrics, and up to 40 comparable rental properties. Investors could filter these comps by property type and amenities to see if projected revenues survived realistic budgeting.
Additionally, the platform provided tools to analyze monthly seasonality, helping investors identify low-occupancy months and determine if they could cover mortgage payments during off-peak periods. It also evaluated the property’s potential performance as a long-term rental or Section 8 housing, establishing a financial floor in the event that local short-term rental bans were enacted.
For tax planning, the report highlighted that BNBCalc’s tax calculator modeled potential 100% bonus depreciation on qualifying components, cost segregation studies, and non-passive tax treatment. Under federal tax rules, if a property’s average guest stay was seven days or less and the owner met material participation requirements, depreciation losses could be used to offset active W-2 income rather than being classified as passive losses. Given the impact of high interest rates on cash flow, the report noted that first-year tax savings could carry more financial weight for an investor than the property’s actual operating income.
“Every state has a top city, which is a very different thing from every state having a deal worth doing.”
What to take from it
Investors looking at yield rankings should use them as starting points rather than final answers. The data highlights several critical practices for evaluating short-term rental opportunities:
- Analyze deals at the address level rather than relying on citywide averages.
- Factor in the full cost of financing and professional management before committing capital.
- Verify local zoning laws and minimum stay requirements directly with municipal authorities.
- Examine seasonal revenue fluctuations to ensure cash flow can cover debt service during off-peak months.
- Evaluate the property’s performance as a long-term rental to establish a financial floor.
Figures checked by the standards desk (Paul Ostrowski): every figure in this story was matched to the source material listed below before publication. The desk's review raised 3 points, corrected before publication.
Sources
- BiggerPockets (Garrett Brown; data from BNBCalc) - published September 8, 2026.
Part of the Booked News record for September 2026. The desk filed this story on October 9, 2026 from a source published in the month it covers, under the same figure rule as the daily news.
Report an error in this story · Corrections policy and log
Related stories
Over a quarter of travelers shift demand to hotels over listing discrepancies
Santa Barbara short-term rental ban to cut coastal tax-paying units to 65
Chatham raises short-term rental registration fee to $325 in second hike in two months
Vrbo plans to raise host commissions to 12% drawing pushback
Read the desk every morning.
Leave your address for the Booked News briefing: the day's figures on rates, occupancy, demand, fees, supply and returns, each with its source, in one short email.
Comments