UK property tax raid to hit Airbnb owners with 4pc income levy
Treasury sources confirmed short-term holiday lets will face higher tax rates on property income, raising £800m annually as part of a broader landlord tax increase.
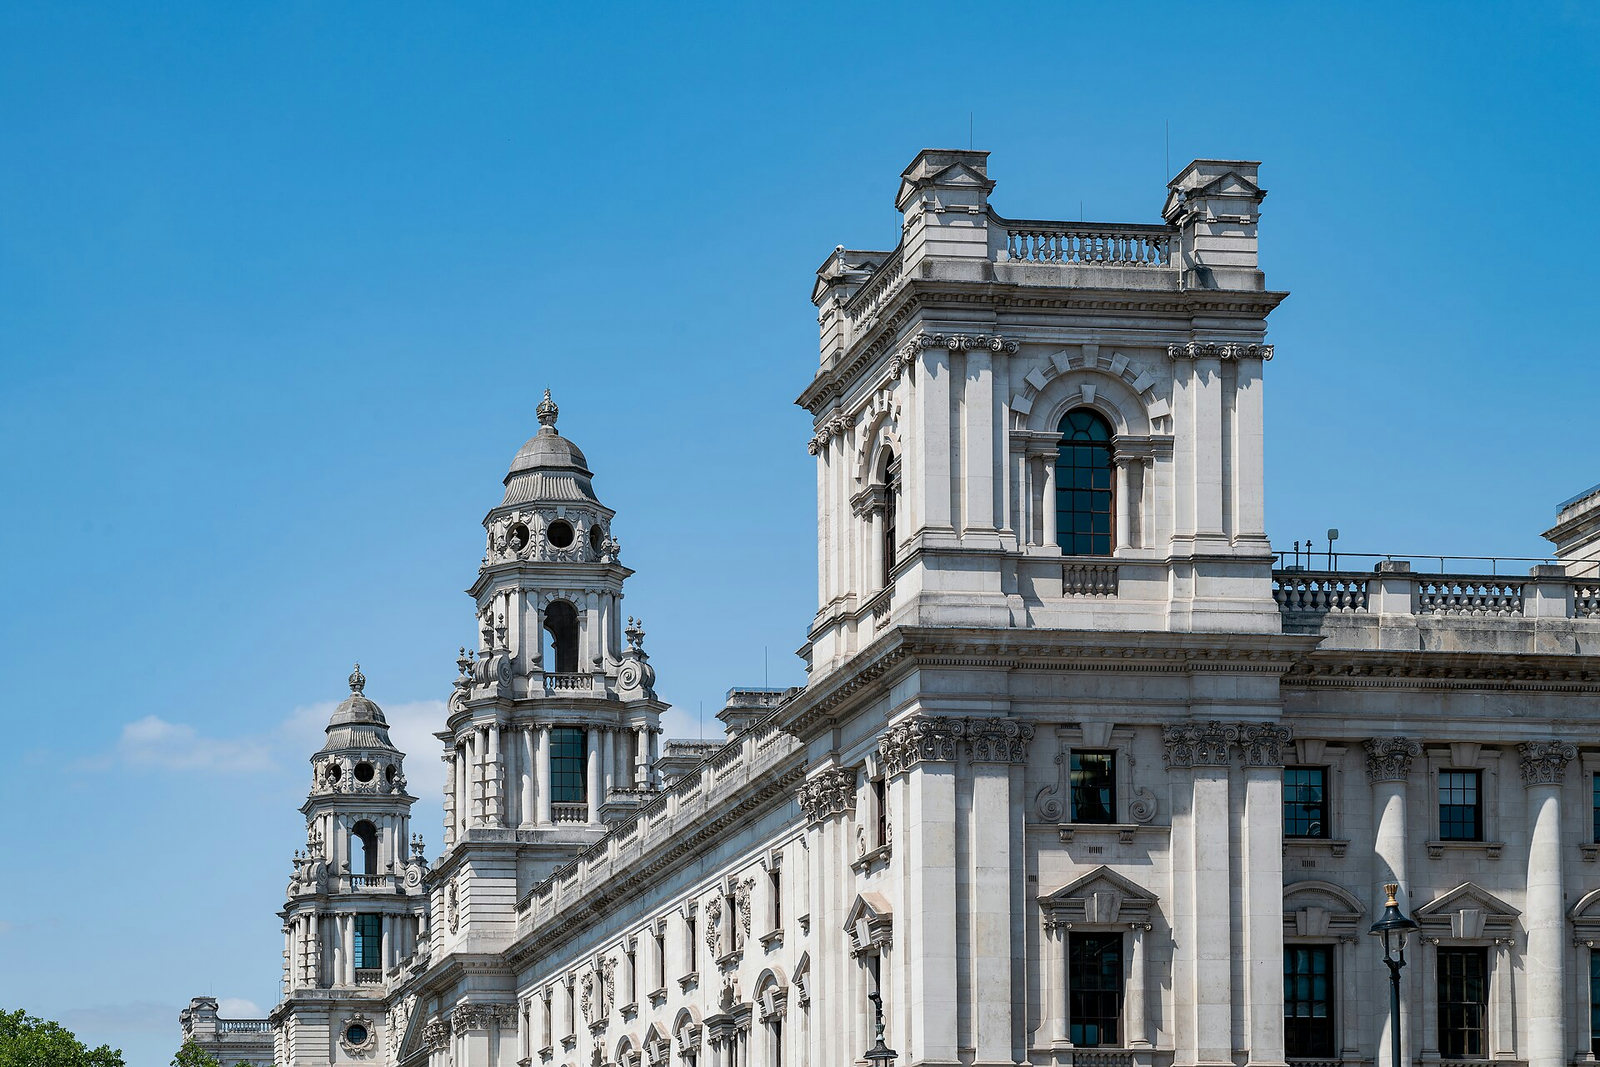
The HM Treasury building on Whitehall in London, photographed in 2025. Picture from Wikimedia Commons: “1066103 II Star New Government Offices (HM Treasury), WHITEHALL SW1 London 20250616 0001”. Photographer Tilman2007. Licence CC BY-SA 4.0. Resized from the original.
The Office for Budget Responsibility estimates that higher rates of property income tax will raise around £1bn in the 2028-29 tax year before settling at around £800m in later years, directly affecting short-term rental hosts across Britain. Treasury sources confirmed that short-term holiday lets will be hit by a 4pc additional tax on property income, expanding a broader tax policy applied to residential landlords.
The tax increases form part of a series of Budget measures announced by Chancellor John Healey on Wednesday to fund public spending commitments, including a £100 energy bills handout to households. The measures adjust tax bands for individual landlords and holiday let operators, following the prior abolition of the furnished holiday lettings regime on April 6 2025.
What the data shows
Official estimates from the Office for Budget Responsibility indicate that the new property income tax rates will generate around £1bn in the 2028-29 tax year. In subsequent years, the policy is expected to bring in around £800m annually to the Treasury.
The tax adjustments change the rates applied to rental earnings across different income tax brackets. Treasury sources confirmed that short-term holiday lets are included alongside long-term residential lettings in the scope of the 4pc additional tax on property income.
Basic-rate income taxpayers will see their tax rate on property income rise from 20pc to 24pc from next April. For taxpayers in higher income bands, the tax rates on rental income will rise to 44pc and 49pc.
The fiscal changes expand on prior announcements. Shadow Chancellor Rachel Reeves had previously signalled a 2p increase in her Budget last November. Chancellor John Healey went further in his Commons statement on Wednesday, introducing higher structural rates across landlord brackets.
Data from HM Revenue and Customs shows the scale of the individual host market affected by these tax shifts. According to HMRC records, around 130,000 individuals declared a total of £2.5bn in profits from holiday lets last year. Industry estimates place total potential supply at an estimated 450,000 Airbnb properties available for short-term lets in Britain. Across major online platforms including Airbnb, Booking.com, and Expedia-owned Vrbo, operators hosted more than 100 million stays last year.
To show the practical financial effect on an individual host, tax advisory firm UK Landlord Tax modeled an example based on a higher-rate taxpayer. According to adviser Pavan Mandir at UK Landlord Tax, an Airbnb owner in the higher-rate tax band making a typical £24,000 profit will see their annual tax bill rise by £960, moving from £9,600 to £10,560.
How it was measured
The figures cited in the Treasury policy rollout draw from multiple government, industry, and advisory sources.
The revenue forecast of £1bn in 2028-29 and £800m in later years was calculated by the Office for Budget Responsibility using government economic modeling of property income tax yields.
The counts of individual taxpayers and total declared profits were measured by HMRC based on self-assessment tax returns submitted for the previous tax year. HMRC reported that around 130,000 individuals declared £2.5bn in total holiday let profits. HMRC figures do not include properties operated under commercial business entities or operations generating earnings below the personal income tax threshold.
The estimate of 450,000 available Airbnb properties in Britain is an industry metric for active short-term inventory. The reported volume of more than 100 million stays last year covers aggregated bookings across Airbnb, Booking.com, and Vrbo.
The specific tax impact figure of a £960 increase was calculated by Pavan Mandir at UK Landlord Tax using standard higher-rate property tax formulas applied to a £24,000 annual net profit baseline.
Tax rate changes by income bracket
The government's revised tax policy alters the yield expectations for property earnings depending on an operator's overall personal income bracket.
Starting next April, basic-rate taxpayers face a rate increase from 20pc to 24pc on property income. This represents a four percentage point rise in statutory liability for lower-tier individual operators.
Landlords and holiday let hosts in higher tax brackets face elevated tax liabilities on rental earnings, with top-tier rates reaching 44pc and 49pc. These changes apply directly to net taxable rental revenue after allowable property expenses.
The policy trajectory builds on tax measures proposed in late 2025. Rachel Reeves signalled a 2p tax adjustment in the November Budget. John Healey's Commons statement on Wednesday introduced additional rate increases across all property income bands. The Treasury confirmed that proceeds from the property tax expansion will help fund specific government expenditure items, such as the £100 energy bills handout for UK households.
Abolition of furnished holiday lettings regime
The tax treatment of short-term rentals in Britain underwent a structural shift prior to the current Budget statement. Short-term holiday lets were not classified as ordinary property businesses until April last year, when the government formally abolished the furnished holiday lettings tax regime.
Prior to April 6 2025, holiday let owners enjoyed dedicated tax allowances, including full interest deductions and capital gains tax reliefs, that were separate from standard residential landlord rules. The abolition of that regime unified short-term lets and residential tenancies under a single tax definition.
Pavan Mandir, adviser at UK Landlord Tax, explained the regulatory status of short-term rentals under current tax law:
blockquote>“Since the furnished holiday lettings regime was abolished from April 6 2025, holiday lets and Airbnb-style lets have formed part of your ordinary property business. That means there is no separate treatment for short-term lets.”
Because short-term lets are now legally defined as ordinary property businesses, any broad increase in property income tax rates automatically hits short-term hosts alongside conventional residential landlords.
Industry impact and operator margins
Industry representatives argue that the cumulative burden of regulatory and tax changes is compressing profit margins for independent tourism operators across Britain.
Alistair Handyside, representative of the Professional Association of Self-Caterers, outlined the operational pressure facing property owners following the announcement:
blockquote>“It is incredibly unhelpful at a time when tourism is under so much pressure; it's yet another payment to find. A lot of people are going to say, 'I've done the maths, it's just not worth it any more.' It's not any individual straw that breaks people; it's the cumulative impact. All the costs are going up and now the Government is taking more, and of course we're not able to put up prices, so everyone's margin decreases again. They can't keep doing that; it just doesn't work.”
The tax rate increases come in addition to pending regional compliance measures. Tourism industry leaders highlighted that hosts already face the prospect of a nationwide “holiday tax” on overnight stays scheduled for implementation from 2028. Combining higher income tax rates with localized visitor levies creates sequential financial demands on property managers and individual owners.
While an estimated 450,000 properties are available on Airbnb in Britain, HMRC records show that only around 130,000 individual taxpayers file holiday let earnings. This gap indicates that a substantial proportion of short-term rental supply is held within limited companies, operates below tax thresholds, or functions as non-taxable secondary space.
Airbnb declined to issue a comment on the tax policy changes.
What the data does not tell you
While OBR and HMRC figures detail total projected revenue and taxpayer counts, the source data leaves several operational and market questions unanswered.
First, the HMRC dataset of 130,000 individuals declaring £2.5bn in profits does not provide a breakdown of corporate holiday let ownership. Properties owned through corporate vehicles, limited liability partnerships, or institutional funds are taxed under corporate tax structures rather than personal property income tax bands.
Second, the figure of 450,000 available Airbnb properties does not specify active occupancy rates, seasonality, or host listing concentration. The data does not show how many of these listings represent primary residences rented occasionally versus dedicated full-time investment properties.
Third, the aggregated figure of more than 100 million stays across Airbnb, Booking.com, and Vrbo does not separate domestic UK travelers from international visitors. It also does not quantify multi-platform cross-listing, where a single physical property is listed simultaneously across all three booking portals.
Finally, the OBR estimate of £800m in annual tax yield does not model potential behavioral changes by hosts, such as property divestment, shifting units into long-term tenancies, or moving holdings into corporate entities to mitigate personal income tax brackets.
What to watch
As the tax policy takes effect next April, operators and investors can track several concrete financial and regulatory markers:
- Review personal income tax brackets to determine whether rental income falls into basic-rate 24pc or higher-rate 44pc and 49pc categories.
- Evaluate corporate entity ownership structures versus individual holding of short-term rental assets.
- Assess baseline net profit margins using the UK Landlord Tax benchmark figure of £24,000 to measure tax liability shifts.
- Monitor local municipal guidance regarding the implementation of the planned 2028 overnight holiday tax.
- Track listing volume changes across Airbnb, Booking.com, and Vrbo to identify market exit or platform consolidation trends.
Figures checked by the standards desk (Paul Ostrowski): every figure in this story was matched to the source material listed below before publication.
Tally from the accuracy gate: 55 details tested; 52 found in the stored source or in the sources listed below; 3 allowed as background knowledge; nothing cut.
Sources
- Yahoo Finance Singapore - reported October 30, 2026.
- mortgagesolutions.co.uk - Autumn Budget 2026: Chancellor delivers landlords an 'underhand blow' with doubled tax rate.
Read and analysed by the Booked News desk.
Is a figure here wrong? Say so / The corrections procedure and the log
Related stories
How property management fees and listing channels shape short-term rental revenue
UK Short-Term Rental RevPAR Holds Firm as Hotels Fall 8% in Q3 2026
Picture from Wikimedia Commons; licence CC BY-SA 4.0; photographer Dominic Nelson
Over a quarter of travelers shift demand to hotels over listing discrepancies
UK forward occupancy for August and September 2026 paced 5% lower as rates rose
Read the desk every morning.
Leave your address for the Booked News briefing: the day's figures on rates, occupancy, demand, fees, supply and returns, each with its source, in one short email.
Comment thread