European short-term rental occupancy rose to 59% in 2025, AirDNA reported in January 2026
AirDNA reported that available listings averaged 3.65 million per month, while average daily rates fell 1.1% to €130.
Updated 15 October 2026. After a source check by the standards desk, 3 sentences were removed because no source confirmed their specifics. Corrections log.
On January 21, 2026, AirDNA reported that available short-term rental listings in Europe averaged 3.65 million per month in 2025, representing a 3.5% year-over-year increase. This growth rate marked a significant deceleration from previous years as regulatory measures took effect across the continent.
Despite the slower pace of new properties entering the market, traveler demand remained strong. European short-term rentals recorded 470 million demand nights in 2025, a 4.4% increase compared to 2024 that helped lift overall occupancy rates.
What the data shows
According to the AirDNA report, the European short-term rental market experienced a transition in 2025. The 3.5% year-over-year increase in average monthly available listings, which reached 3.65 million, was a sharp departure from the rapid expansion seen in the prior year. For comparison, the year-over-year increase in available listings from 2023 to 2024 was 18.1%.
AirDNA reported that monthly supply growth in 2025 was split into two distinct halves. The first six months of the year recorded the highest year-over-year growth rates, averaging 4.7%. Supply growth then slowed significantly in the summer, with July and August experiencing the lowest growth rates at 0.7% and 1.3%, respectively. Supply growth steadily recovered in the autumn and ended the year at 3.1% in December. An analysis of new listings, which includes properties entering the market for the first time, showed a continued slowdown throughout 2025. AirDNA observed a 9.9% decrease in new listing totals in 2025 compared to 2024. When compared to the pre-pandemic baseline of 2019, new listings in 2025 were 12% lower.
Demand for short-term rentals in Europe reached a record high of 470 million nights in 2025, representing a 4.4% year-over-year increase. This demand growth outpaced the expansion of available listings. AirDNA reported that April stood out with the highest year-over-year demand growth at 19%, driven by the calendar shift that moved Easter from March into April. However, the second half of the year experienced a notable slowdown. Year-over-year demand growth since August remained below 1%, with declines of 3% in November and 1.1% in December.
Nights booked in 2025, which include reservations made during the reporting month for stays in the current month or in January 2026, totaled 484 million nights, representing a 3.7% increase from 2024. AirDNA noted a shift in the monthly distribution of bookings, with most bookings in 2025 occurring in the first quarter of the year due to economic and political uncertainties. Ten percent of the annual nights booked were made in January alone, whereas in previous years, the third quarter recorded the highest volume of bookings.
Because demand outpaced supply, the average continental occupancy rate in Europe rose by 0.7% year-over-year to 58.7% (reported as 59% in the summary metrics). This stood in contrast to 2024, when sharp supply increases caused occupancy to decline by 5.2% year-over-year. Occupancy in Europe also grew more quickly than occupancy in the United States, where occupancy increased by 0.3% to 57% over the same period.
Pricing and revenue metrics showed mixed results. Average Daily Rates (ADR) in Europe declined for the second consecutive year, falling by 1.1% year-over-year to €130. This followed a 2.9% decrease in ADR in 2024. Despite the drop in ADR, the Repeat Rent Index (RRI), which tracks price changes among existing operators and excludes the impact of new listings, grew on average by 3%. The RRI experienced eleven months of growth, particularly during the summer months when the average year-over-year increase was 4.1%.
Revenue per Available Rental Night (RevPAR) decreased by 0.4% year-over-year to €76. AirDNA noted that while RevPAR declined slightly, this represented a recovery after an 8% decline in 2024. Total revenue for short-term rentals in Europe increased by 3.2%, reaching €61 billion.
How it was measured
The figures were compiled and analyzed by AirDNA, a short-term rental data and analytics provider. The data covers the full calendar year of 2025, comparing performance metrics against 2024 and the pre-pandemic baseline of 2019.
AirDNA measured supply by calculating the average number of available listings, which includes the total number of properties listed and open for bookings. Demand was measured in demand nights, representing the total nights stayed in short-term rentals during the year. Nights booked tracked reservations made during a reporting month for current stays or stays in January 2026.
To analyze pricing trends more accurately, AirDNA utilized the Repeat Rent Index (RRI). The RRI tracks price changes specifically for existing operators and removes the impact of new listings, which helps isolate the pricing power of established hosts from the downward pressure of underpriced new entrants. Additionally, AirDNA used pricing variability as a proxy for measuring the adoption of revenue management systems among hosts. Data regarding visitor origins in Prague was provided by Prague's Tourism Association.
National market disparities
Performance varied widely among the top 20 European nations. Despite rising regulatory pressures, the average number of available listings increased in 17 of Europe’s top 20 countries. However, three countries experienced supply declines: Croatia fell 2.8%, Spain fell 2.2%, and Italy fell 0.9%. Since 2019, Croatia has seen a consistent decline and ended 2025 with 21.6% fewer listings than in 2019. In Spain, regulatory pressures imposed by the government caused tens of thousands of listings to be delisted, while Italy’s decline was attributed to stricter regulations, including higher taxes for multi-listing hosts and more structured registration procedures.
On the other hand, multiple nations experienced strong supply growth. Norway rose 17.4%, the Czech Republic rose 13.7%, Finland rose 12.3%, and Germany rose 9.6%. Germany established itself as the fourth-largest short-term rental market in Europe. The other top five nations—France, Italy, Spain, and the United Kingdom—failed to achieve supply growth above 3% in 2025. Germany significantly outperformed them, while France experienced steady supply growth at 2.4% and the United Kingdom grew by 3%. The United Kingdom recorded the second-highest growth rate among Europe's five largest markets, and AirDNA noted that if these trends continue into 2026, the United Kingdom could surpass Spain to become the third-largest market in Europe.
In terms of demand, combined demand nights among Europe's top 20 nations grew by 4%, slightly lower than the continental growth of 4.4%. The top performers for demand growth were the Czech Republic at 16.7%, Norway at 14.2%, and Poland at 12.3%. Performance among Europe's five largest markets was mixed: Germany grew 6.5%, France grew 5%, the United Kingdom grew 4.7%, Spain grew 1.6%, Italy fell 0.4%, and Croatia fell 7.3%. Croatia's demand in 2025 fell 21.1% short of its 2019 level.
City-level regulatory impacts
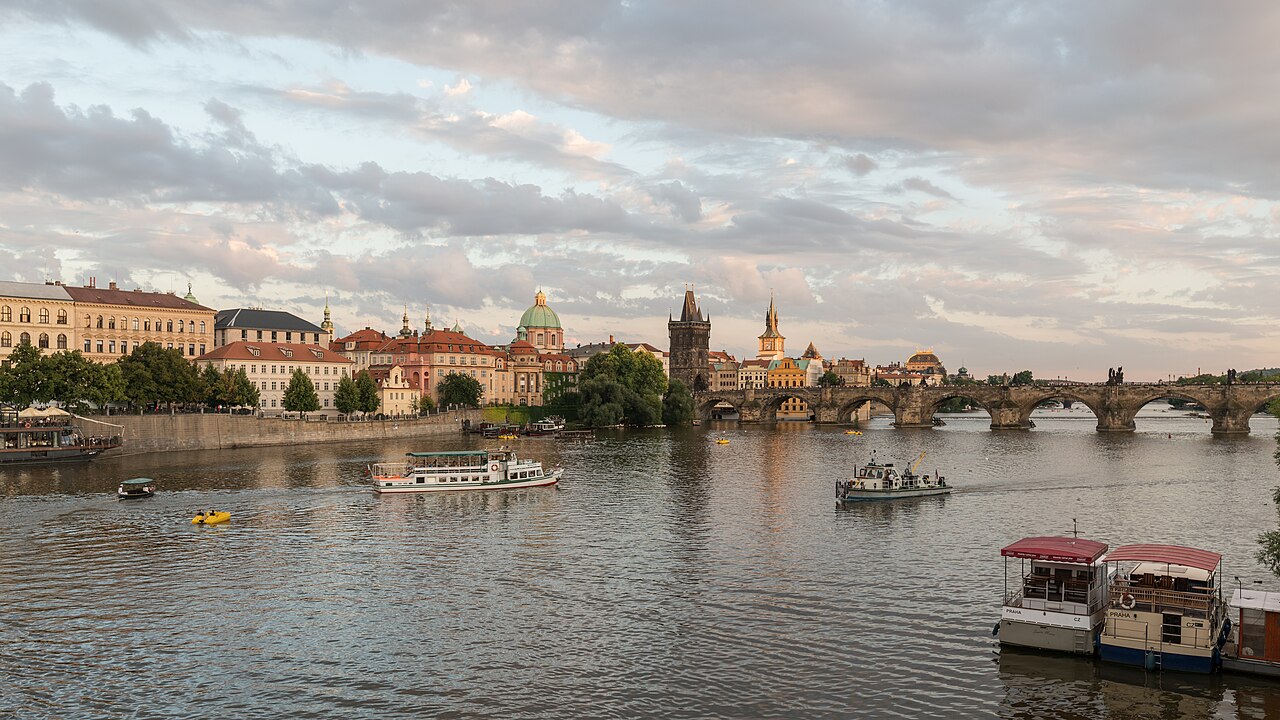
As municipal regulations tightened across Europe, cities experienced some of the strictest enforcement. By 2025, only 22 of the top 50 European cities saw an increase in available listings. Prague led this group with a 9.4% year-over-year growth rate in supply. Conversely, Paris experienced the largest decline, with a 17.1% drop in supply. This decrease followed a surge in listings by opportunistic hosts during the 2024 Paris Olympics, which then receded from the market.
Compared to the pre-pandemic baseline of 2019, the tightening regulations were more evident. Only 17 of the top 50 cities had more listings in 2025 than in 2019. The three cities experiencing the largest declines were all German hubs: Berlin fell 59%, Cologne fell 54%, and Hamburg fell 46%. AirDNA attributed these declines to increasing pressure on residential housing in major cities.
Demand nights in Europe’s top 50 cities grew by 4.6% overall, with 31 of the 50 cities seeing positive growth. Prague rose 16.4%, Krakow rose 14.7%, and Rome rose 14.2%. In Prague, demand rose significantly due to an increase in direct flight routes from Canada, East Asia, and Arab nations, with Asian visitors increasing by 12% according to Prague's Tourism Association.
In Krakow, travelers sought more budget-friendly options as inflation sapped spending power. Krakow's ADR was 34% below the average of the top 50 European cities. Demand growth in Krakow was especially noticeable during the shoulder months of September and October, which saw a 40% increase compared to just a 9% rise over the summer.
In Italy, the Jubilee Year in Rome significantly increased demand, boosting it by 14.2%. This marked a notable deviation from the national trend of a 0.4% decline. Meanwhile, Milan experienced 2.8% demand growth and Florence saw a 1.9% increase, while Naples fell 0.4% and Turin fell 2.5%.
Occupancy gains were highly concentrated, with only 21 of the top 50 cities seeing higher occupancy. Paris had the largest occupancy increase, driven by the combination of a 17.1% supply contraction and 8.6% demand growth. Marseille saw occupancy rise mainly because supply contracted quickly, despite a demand slowdown of 3.6%. Malaga experienced a modest 0.4% rise in occupancy despite an 8.6% surge in demand, because available listings increased by only 1.4% following the announcement of a three-year suspension of new permits for short-term rentals.
Traveler demographics and revenue management
AirDNA identified a clear shift in traveler origins between northern and southern Europe in 2025. Spain and Italy experienced notable declines in domestic demand, dropping by 4.3% and 3.3% respectively, though their markets were supported by a rebound in international visitors. Conversely, Germany and the United Kingdom depended largely on domestic travel to counteract decreases in foreign arrivals. Germany’s domestic travel share grew by 3.2%, compensating for a 3.6% decrease in foreign demand. Similarly, the United Kingdom saw a 1.8% increase in domestic travelers.
Another key trend in 2025 was the slow adoption of revenue management systems in Europe compared to the United States. AirDNA used pricing variability as a proxy for measuring this adoption. In France, Europe's largest market, only 19% of listings had highly variable rates, compared to 52% of listings deploying dynamic pricing in the United States. Only Poland, Hungary, and the Netherlands showed revenue management adoption rates similar to the United States, despite being smaller markets.
The top five European nations lagged considerably behind in pricing variability. The percentage of hosts using revenue management strategies within these major markets was less than half: the United Kingdom was at 33%, Spain was at 24%, Italy was at 23%, France was at 19%, and Germany was at 10%.
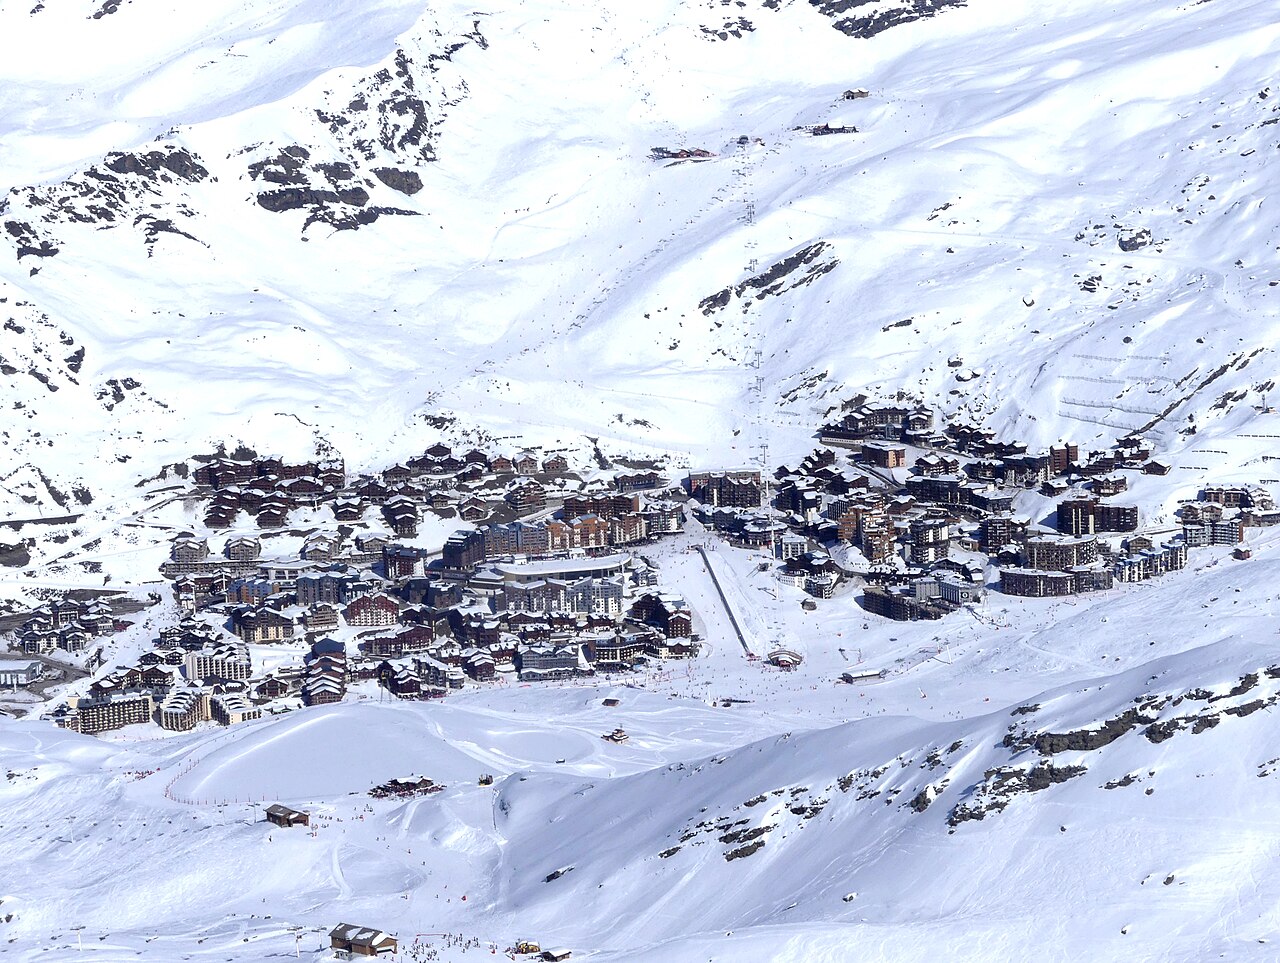
Ski destination demand pacing
European ski destinations were expected to continue attracting visitors in the first quarter of 2026.
What to take from it
Understanding these performance shifts helps operators prepare for changing market conditions in the coming years.
- Monitor local regulatory announcements closely, as suspensions of new permits or strict registration rules can instantly restrict supply and alter local occupancy dynamics.
- Evaluate the balance between domestic and international demand in your specific region to tailor marketing and booking windows.
- Adopt dynamic pricing tools to close the operational gap, especially in major markets like Germany and France where adoption remains exceptionally low.
- Track shoulder-season demand trends, as budget-conscious travelers are increasingly shifting their stays outside of peak summer months.
Figures checked by the standards desk (Paul Ostrowski): every figure in this story was matched to the source material listed below before publication. The desk's review raised 1 point, corrected before publication.
Sources
- AirDNA - published January 21, 2026.
Part of the Booked News record for January 2026. The desk filed this story on October 9, 2026 from a source published in the month it covers, under the same figure rule as the daily news.
Re-checked by the standards desk on 15 October 2026 against the original sources and a public-source lookup: 3 sentences were removed because no source confirmed their specifics.
Report an error in this story · Corrections policy and log
Related stories
European short-term rental rates rose 8.2% in July 2026 as occupancy steadied
European short-term rental rates rose 8.2% in March 2026 as supply growth accelerated
European short-term rental supply rose 1.8% in October 2025 as demand softened
European short-term rental listings reached 4 million in September 2025 as growth slowed
Read the desk every morning.
Leave your address for the Booked News briefing: the day's figures on rates, occupancy, demand, fees, supply and returns, each with its source, in one short email.
Comments