U.S. short-term rental rates rose 6.9% in July 2026 as supply growth flattened
AirDNA reported that average daily rates reached $317.55 in July 2026, while high mortgage rates kept new listing supply flat at 2.6%.
On August 13, 2026, AirDNA reported that U.S. short-term rental performance strengthened in July 2026, with average daily rates climbing to $317.55, representing a 6.9% increase from the previous year. This pricing momentum was supported by a slight rise in occupancy and a significant broadening of rate growth across almost all major metropolitan markets, even as the international soccer matches that had previously concentrated demand began to wind down.
The performance gains recorded during the month occurred against a backdrop of tightening monetary conditions and a cooling labor market, which combined to limit the expansion of new short-term rental supply. While the soccer tournament provided a substantial and lasting lift to host cities, the broader market experienced a general upward trend in pricing, demand, and booking lead times, indicating stable consumer interest despite macroeconomic headwinds.
What the data shows
The data released by AirDNA showed positive movement across several key performance indicators for the U.S. short-term rental market in July 2026. Revenue per available rental rose 7.2% year-over-year to reach $217.17. This increase was driven by a combination of higher average daily rates and a minor improvement in occupancy. The average daily rate climbed 6.9% from July 2025 to reach $317.55, while occupancy averaged 68.4%, representing a 0.3% increase compared to the same month in the previous year.
The total volume of available listings in the United States reached 1.75 million in July 2026, which was a 2.6% increase compared to July 2025. Demand nights grew 2.0% year-over-year, and total nights booked rose 6.9% compared to the previous year. Pricing power was particularly strong among established operators; the AirDNA Repeat Rent Index, which tracks price changes for the same properties over time to exclude changes in market composition, rose 8.1% year-over-year.
This rate growth was distributed widely across the country rather than being concentrated in a few high-performing areas. AirDNA reported that average daily rates rose in 49 of the top 50 short-term rental markets in the United States, with 41 of those markets recording rate increases of more than 5%.
How it was measured
The figures were compiled and analyzed by AirDNA, a short-term rental data and analytics provider, in its monthly market review published on August 13, 2026. The organization tracked performance metrics for the U.S. market during the month of July 2026, comparing the results against historical data from July 2025.
To evaluate underlying pricing trends without the distorting effects of new properties entering or leaving the market, AirDNA utilized its Repeat Rent Index. This index measures price changes specifically for properties that have been active over a longer period, allowing the organization to isolate organic rate growth from changes in the overall mix of available listings. The source did not publish its exact underlying data collection method or sample size in the report, but noted it tracks performance metrics like RevPAR, ADR, available listings, and occupancy across the United States.
Economic conditions and supply constraints
The performance of the short-term rental market in July 2026 was heavily influenced by broader economic conditions, particularly in the housing and labor sectors. Monetary conditions continued to tighten during the month as the Federal Reserve kept its target for short-term interest rates unchanged due to ongoing inflation concerns. Consequently, mortgage rates experienced upward pressure. The rate for a 30-year fixed-rate mortgage rose 23 basis points during July 2026, starting at 6.43% in the first week and ending the month at 6.65%.
This upward movement in mortgage rates contradicted earlier projections. AirDNA had initially expected mortgage rates to decline gradually throughout 2026 to around or below 6%. Instead, rates trended upward following the start of the war on Iran in late February 2026. This increase reduced the affordability of new mortgage debt and kept the U.S. housing market in a state of low activity.
For the short-term rental sector, these high interest rates prevented supply growth from accelerating as previously expected. Instead, supply growth flattened to approximately 2.5% for the year 2026. Available listing growth remained at or below 2.6% since February 2026, matching the 2.6% year-over-year increase recorded in July 2026. AirDNA noted that because changes in interest rates typically take five to six months to reflect in new short-term rental listing growth, some of the positive effects of lower mortgage rates from the second half of 2025 and January 2026 were still supporting the market in July 2026, but these effects were expected to fade in the second half of 2026.
At the same time, the labor market showed signs of cooling. According to the Bureau of Labor Statistics, the United States lost 23,000 jobs in July 2026. Additionally, the job growth figure for June 2026 was revised downward by 66,000 jobs. While the unemployment rate fell slightly to 4.1% in July 2026 from 4.2% in June 2026, this decline was entirely due to a drop in the labor force participation rate. The participation rate fell to 61.4% in July 2026, down from 61.5% in June 2026. Over the course of the year, the participation rate dropped 100 basis points from the 62.4% recorded at the end of 2025, marking the fastest decline in participation since the Great Recession, excluding the pandemic period. This cooling labor market, combined with inflation dropping from 4.2% in May 2026 to 3.5% in June 2026, reduced the likelihood of further interest rate hikes, though mortgage rates remained high enough to limit new rental supply.
World Cup markets and regulatory impacts
The distribution of listing growth and pricing gains in July 2026 highlighted the significant influence of the World Cup matches and local municipal regulations. While national listing growth was low, cities hosting World Cup matches saw substantial activity. AirDNA reported that eight of the top 12 markets for supply growth in the United States were host cities for the international tournament.
Prior to April 2026, World Cup host markets had actually detracted from national listing growth, but after that month, they contributed strongly to the supply of available rentals. In contrast, the rest of the United States experienced decelerating listing growth since February 2026, with supply growth falling below 2% in both June and July 2026.
Local regulations played a major role in determining where supply could expand. Los Angeles was the only California market to record an increase in available listings, with a modest rise of 1.6%. San Francisco, despite its proximity to the World Cup venue in Santa Clara, saw available listings fall 8.4%, which was the second-largest decline among the top 50 U.S. markets. The largest overall decline in listings occurred in New Orleans, where available listings fell 11.8% year-over-year following increased enforcement of local short-term rental regulations after the city hosted the Super Bowl in 2025.
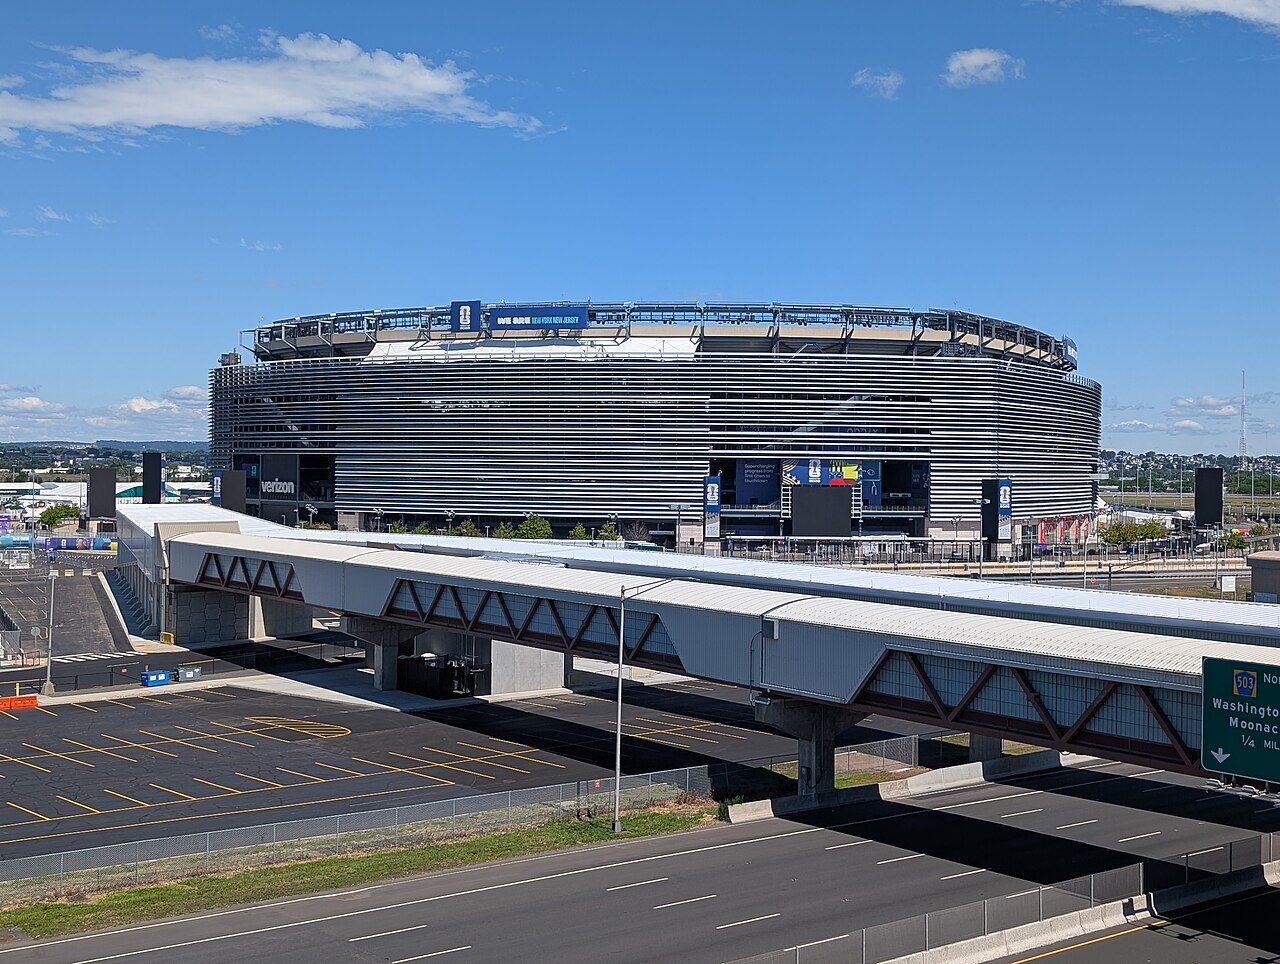
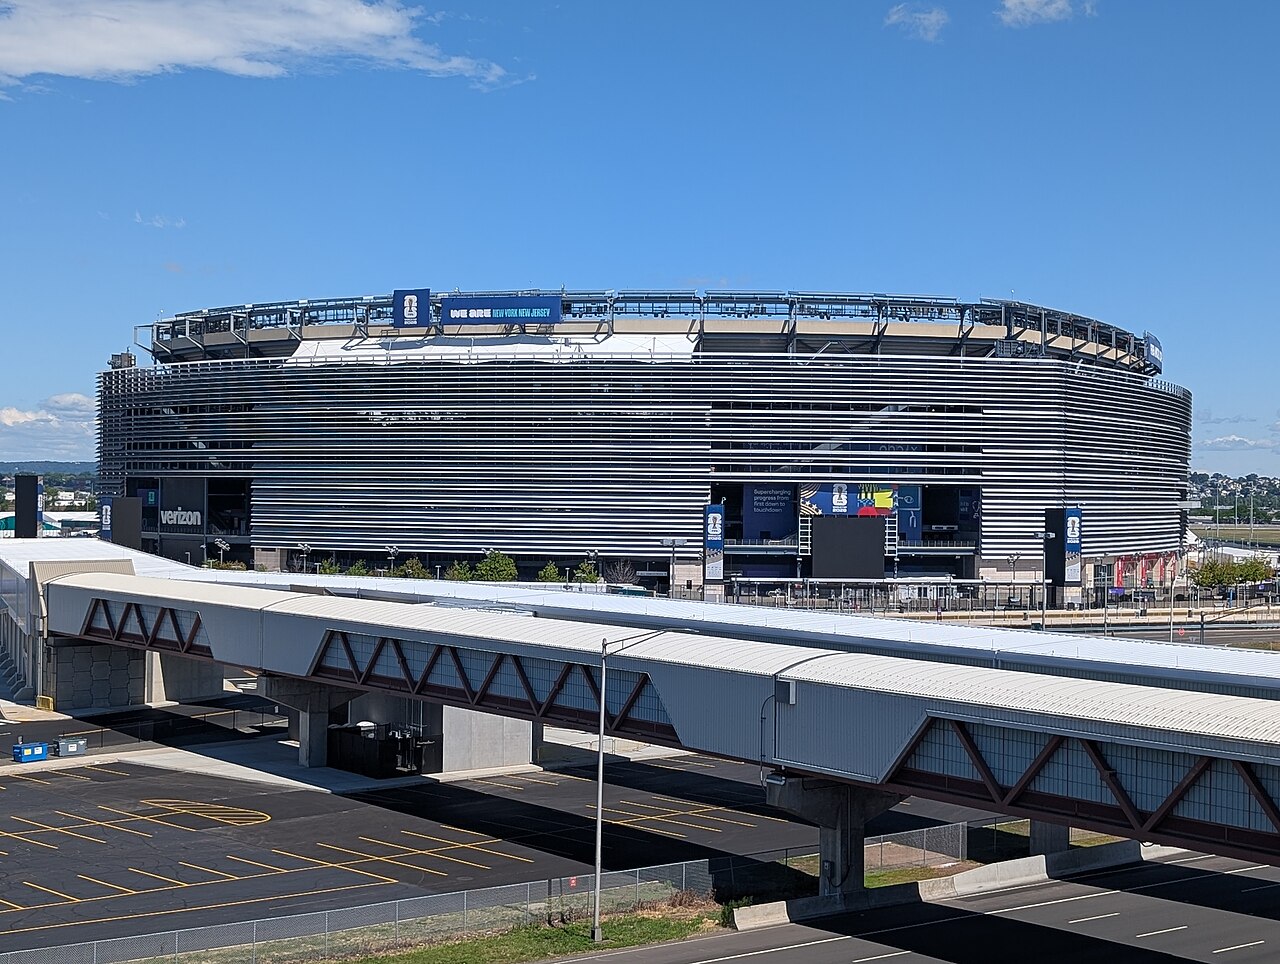
On the pricing side, World Cup host cities and adjacent markets dominated the highest growth rates. Jersey City and Newark, which served the final match of the tournament, recorded the highest average daily rate growth in the country, with rates rising 33.4% year-over-year. Fort Lauderdale recorded the third-highest rate growth, with average daily rates increasing 20.3% compared to the previous year. Several other host cities continued to experience substantial year-over-year pricing lifts in July 2026 despite hosting only a single match during that month:
- Philadelphia average daily rates rose 18.0% year-over-year.
- Boston average daily rates rose 16.8% year-over-year.
- Seattle average daily rates rose 16.3% year-over-year.
Pacing variations and booking lead times
The forward-looking outlook for the short-term rental market in the second half of 2026 was characterized by strong pacing data, though specific calendar shifts and booking behaviors introduced some complexity. Pacing data, which compares active reservations on the books with reservations held at the same point in the prior year, indicated that demand for each month after August 2026 was pacing more than 15% ahead of the previous year.
However, AirDNA identified two specific data issues that affected these figures. First, a calendar shift moved the Labor Day holiday weekend from August to September in 2026. This shift artificially lowered demand for August 2026 while inflating September's demand, potentially accounting for 5% to 8% of the demand recorded for September.
Second, booking lead times—the number of days before a stay that a guest makes a reservation—altered the pacing comparison. Lead times had been in a multi-year decline before rising in October and November 2025, followed by several months of decline and then four months of either longer or stable lead times leading into July 2026. While longer lead times in June and July 2026 might have suggested an increase in long-term planning by international travelers, the data showed that lead times actually fell in some key areas. In Coastal Resort locations, average lead times for June and July 2026 declined by an average of two days. In Urban locations, lead times fell by one day in June 2026 and remained flat in July 2026. Because longer lead times cause reservations to be recorded earlier in the cycle, they can artificially inflate pacing figures without representing a true increase in final realized demand.
International demand trends
The completion of the World Cup matches allowed for an assessment of international travel trends, which had been under pressure since May 2025 following the announcement of the "Liberation Day" tariffs. International demand had recorded 13 consecutive months of year-over-year declines before rising 9.4% in June 2026 during the group stage of the tournament.
In July 2026, international demand growth slowed, rising only 0.7% year-over-year, which followed a 9.8% decline in July 2025. This indicated that while the tournament stopped the decline in international bookings, the strongest international draw was concentrated in the earlier stages of the event.
Canadian guest demand, which had experienced the most significant declines since the tariff announcements, showed steady improvement during the tournament period. Canadian demand rose 2.9% year-over-year in June 2026 and rose 5.8% year-over-year in July 2026. Despite these gains, the recovery remained partial. When compared to the levels recorded two years prior, before the tariffs were finalized, Canadian demand in July 2026 was still down 41.8%, highlighting the long-term impact of trade policy on cross-border travel.
What to take from it
The performance metrics from July 2026 offer several key insights for short-term rental operators, property managers, and investors assessing market health and pricing strategies.
- Compare individual property rate increases against both the standard average daily rate growth and the Repeat Rent Index to determine whether local pricing power is driven by market-wide inflation or property-specific advantages like guest reviews.
- Monitor local regulatory enforcement trends, as seen in New Orleans and San Francisco, which can cause sudden double-digit drops in supply and alter the competitive landscape regardless of major event demand.
- Adjust revenue management systems to account for calendar shifts, such as the movement of holiday weekends between August and September, to avoid misinterpreting temporary pacing spikes as permanent demand growth.
- Track the lag between interest rate movements and local listing supply, keeping in mind the typical five- to six-month delay before mortgage rate changes influence new rental inventory.
Figures checked by the standards desk (Paul Ostrowski): every figure in this story was matched to the source material listed below before publication. The desk's review found nothing to correct.
Sources
- AirDNA - published August 13, 2026.
Part of the Booked News record for August 2026. The desk filed this story on October 9, 2026 from a source published in the month it covers, under the same figure rule as the daily news.
Report an error in this story · Corrections policy and log
Related stories
U.S. short-term rental supply growth accelerated to 3.5% in April 2026
U.S. short-term rental RevPAR rose 4.5% in June 2026
U.S. short-term rental occupancy rose to 57.2% in May 2026
U.S. short-term rental occupancy averaged 61.3% in March 2026
Read the desk every morning.
Leave your address for the Booked News briefing: the day's figures on rates, occupancy, demand, fees, supply and returns, each with its source, in one short email.
Comments