How listed monthly rents measure urban accommodation demand across gateway markets
global rental tracking shows listed asking rents stabilizing across core metropolitan markets as seasonal demand shifts and operating expenses squeeze operator returns.
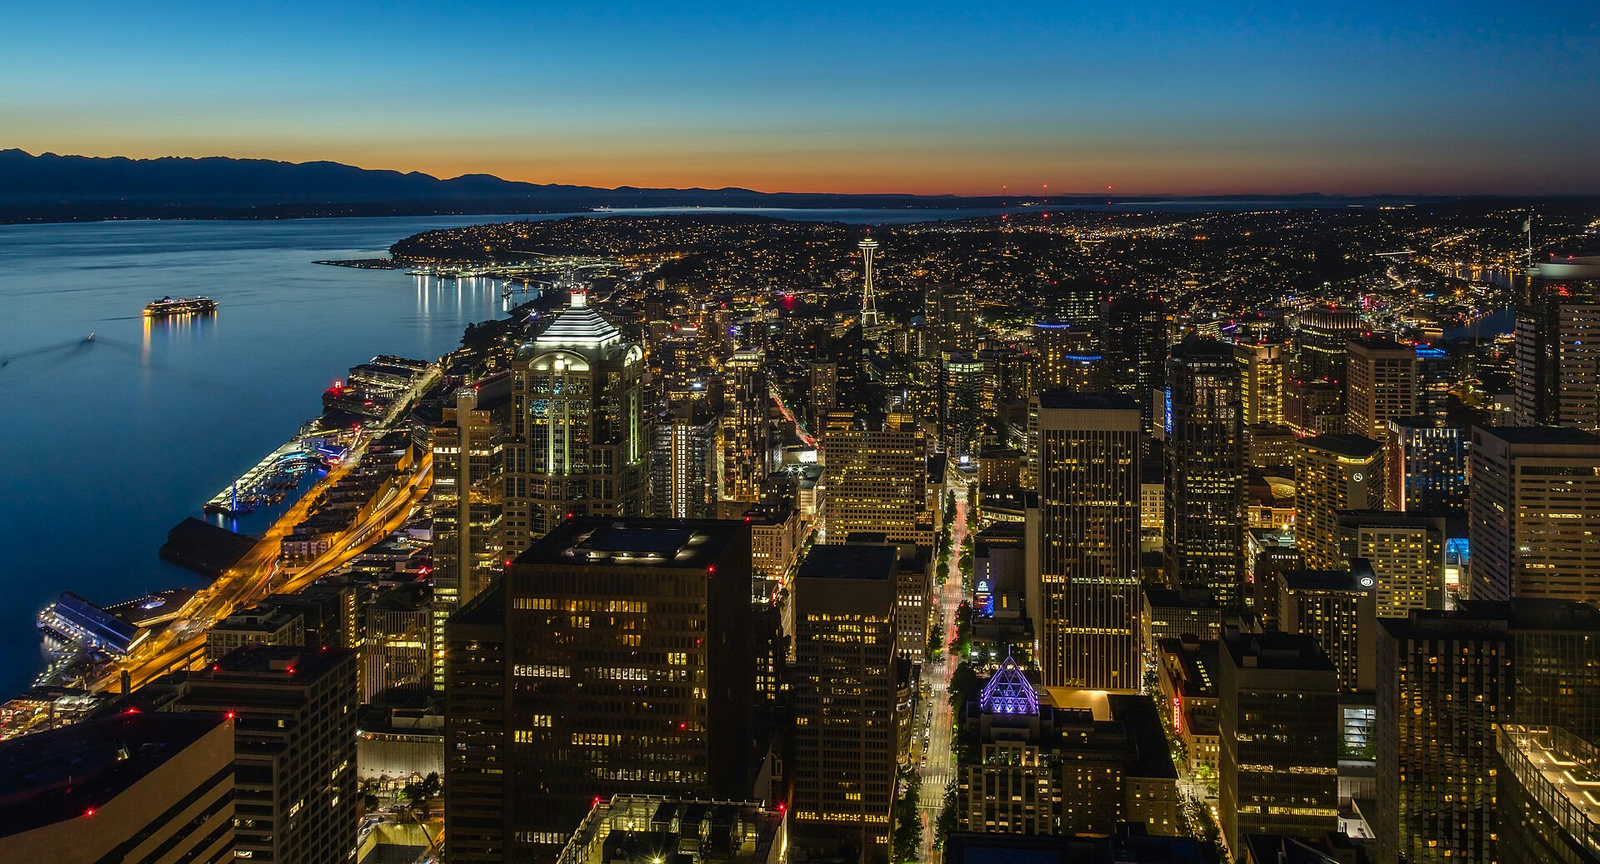
The city skyline of Seattle at dusk, photographed from the Columbia Center in 2017. Picture from Wikimedia Commons: “Vista de Seattle, Washington, Estados Unidos, 2017-09-02, DD 07-08 HDR”. Photographer Diego Delso. Licence CC BY-SA 4.0. Resized from the original.
According to statistics from HomeLet and Zoopla, the average listed rent across the UK rose to £1,387 per month in September 2026, driven by university enrollments and international workplace relocations. At the same time, monitoring data from the Asia Travel & Hospitality Big Data Research Institute shows global residential rental markets entering a seasonal correction, with landlord asking prices stabilizing or softening across gateway cities in North America, Europe, and the Asia-Pacific region.
For short-term rental operators, property managers, and institutional hospitality investors, listed rent metrics provide an operational benchmark for baseline residential accommodation value. When listed asking rents in prime urban centers flatten or shift sideways, operators must assess how underlying demand drivers—ranging from student arrivals and corporate transfers to international travel and localized tax policies—interact with rising operational overhead.
How the metric works
Listed rent measures the asking price published by property owners, managers, and real estate platforms for residential units before lease negotiations or occupancy adjustments occur. Unlike completed contract lease rates or realized short-term daily room yields, listed rent represents the prevailing asking baseline in a given municipal or regional market. It reflects landlord expectations, current inventory pressure, and top-level consumer demand.
In urban property analysis, asking rents act as an anchor for flexible hospitality pricing. When long-term listed rents in core downtown districts remain high, short-term rental operators can maintain higher baseline pricing without losing competitiveness against local housing alternatives. Conversely, when long-term asking rents experience seasonal declines or landlord concessions, short-term and medium-term operators often adjust minimum length-of-stay requirements and night rates to retain occupancy.
In the United States, the Zillow Observed Index recorded a national average listed rent of $1,932 per month in September 2026, alongside a national median listed rent of $1,833 per month. Regional divergence remains wide across American metropolitan areas. Coastal financial and technology hubs continue to report elevated asking prices: average listed rents in San Francisco reached $3,400–$4,750 per month, while median rents in San Jose stood at $3,310–$3,800 per month. In New York, tight housing supply held median asking rents at $3,615–$3,695 per month. In the Midwest, Chicago maintained steady performance with an average rent of $2,022 per month, whereas Sun Belt markets such as Austin saw average listed rents adjust to $1,620–$1,986 per month following extensive multi-family construction.
European urban centers reflect similar localized variance. Platform tracking from Immobiliare.it established the national median monthly rent in Italy at 934 euros. Milan led Italian cities with an average listed rent of 22.32 euros/㎡/month, followed by Florence at 21.75 euros/㎡/month, Rome at 19.13 euros/㎡/month, and Bologna at 16.51 euros/㎡/month. In the UK, HomeLet and Zoopla recorded an average rent of £2,272 per month in Greater London, with newly listed high-quality apartments in core Zone 1-2 districts approaching £2,750–£2,800 per month.
How it was measured
The figures in this analysis stem from September 2026 market monitoring published by the Asia Travel & Hospitality Big Data Research Institute, alongside platform-level data from Zillow, HomeLet, Zoopla, Immobiliare.it, CoreLogic, and SQM Research. Additionally, institutional investment perspectives are drawn from statements by Minas Terlidis, Co-Founder and Chief Executive Officer of Bohopo.
Data providers gathered listed asking prices across public real estate portals, estate agency feeds, and institutional rental property registries during late summer and early autumn 2026. Figures for the United States, United Kingdom, Italy, Australia, and Singapore reflect listed monthly or weekly asking prices for residential apartments and single-family rental inventory, excluding final discounted contract figures or tenant-paid utility add-ons unless specifically noted in regional platforms.
Drivers of urban rent movements
Urban rental metrics move according to demographic flows, seasonal calendar events, incoming housing supply, and macroeconomic policy interventions. In autumn, student enrollments and corporate hiring cycles generate temporary spikes in gateway city demand, after which market activity enters seasonal consolidation.
In the UK, regional rent growth matched educational and employment concentration. HomeLet and Zoopla data showed average rents in southwest England reaching £1,274 per month, representing a 5.4% year-on-year increase. Rents in Scotland reached £1,060–£1,070 per month, supported by student arrivals in Edinburgh and Glasgow for a 4.9% year-on-year increase. Southeast England reached £1,472 per month, up 1.8% year-on-year, while eastern England recorded £1,340 per month, up 2.0% year-on-year.
In Australia, CoreLogic and SQM Research reported a national median weekly rent of 627 Australian dollars per week, equivalent to approximately 2,717 Australian dollars per month. City-level data demonstrated varied monthly trajectories during September 2026:
- Sydney registered a median weekly rent of 780–840 Australian dollars per week, down 0.2% month-on-month.
- Melbourne recorded a median weekly rent of 575–640 Australian dollars per week, up 0.1% month-on-month.
- Brisbane reached a median weekly rent of 630–670 Australian dollars per week, down 0.1% month-on-month.
- Perth maintained a vacancy rate of 0.7%, with median weekly rents reaching 680–720 Australian dollars per week.
Government policy also dictates foreign tenant demand and pricing dynamics. In Singapore, median listed apartment rents across the island stood at 4,300–4,800 Singapore dollars per month. By unit size, one-bedroom units asked 3,100–4,100 Singapore dollars per month, two-bedroom units asked 4,000–5,500 Singapore dollars per month, and three-bedroom units asked 5,200–7,200 Singapore dollars per month. Public Housing Development Board (HDB) rental growth slowed to 3.2% annually, with 3-room units asking 2,800–3,300 Singapore dollars per month, 4-room units asking 3,400–3,900 Singapore dollars per month, and 5-room units asking 3,800–4,400 Singapore dollars per month. A tax policy imposing an additional 60% buyer's stamp duty on foreign buyers who do not hold Permanent Resident status has directed high-paid foreign professionals toward long-term transition rentals, stabilizing mid-to-high-end private residential demand despite incoming private housing supply in suburban areas such as Lentor and North Tampines.
Operating costs and yield compression
While top-line asking rents remain elevated across many international gateway cities, net operational returns depend heavily on managing expenses. Short-term and long-term accommodation providers face growing margin pressure from non-negotiable overhead items.
In institutional hospitality, operating costs rank as the primary factor influencing profitability. Speaking on European urban hospitality strategies, Minas Terlidis highlighted the operational pressures facing urban assets:
“Operating costs come first because they decide who actually makes money. Wages, energy, insurance and maintenance keep going up. So investors will look much harder at how efficiently a hotel can be run, and whether the concept really suits its market.”
When room rates and residential listed rents reach consumer affordability ceilings, operators cannot automatically pass cost increases to tenants or guests. Terlidis noted that major transactions continue in primary European business hubs, citing a deal in April when Covivio acquired four hotels in Milan through a sale and leaseback structure. Investors tracking European markets evaluate cities like Athens, where Terlidis has invested since 2015, alongside Porto and Milan, where strong leisure, corporate, fashion, and event demand coincide with constrained central street space.
Regulatory constraints and supply limits
Municipal regulation forms another key structural influence on urban rental metrics. Regulatory actions restrict listing volume and hotel inventory in historical urban centers, placing a floor under existing licensed property valuations.
Terlidis noted that cities such as Amsterdam and Barcelona are tightening rules on short-term rentals and limiting new hotel capacity in city centers. These policy restrictions reduce unlicensed competition for existing licensed operators, preserving room rates and listing demand in supply-constrained historic districts.
At the same time, adaptive re-use of existing commercial buildings—such as townhouses, offices, and warehouses—has become a key vehicle for expanding urban rooms-led inventory. Conversion projects provide entry to central urban locations where greenfield land is unavailable, though developers face complex planning, fire safety, building code, and heritage requirements across different jurisdictions.
What to watch
Operators, managers, and institutional investors monitoring urban rental markets should track these operational indicators over coming quarters:
- Regional vacancy rates in key growth markets, such as Perth's 0.7% vacancy rate, to gauge landlord pricing power.
- The impact of local taxation policies, including Singapore's 60% buyer's stamp duty on foreign non-PR buyers, on long-term tenant absorption.
- Municipal regulatory updates capping short-term rental licenses or hotel development in European centers like Amsterdam and Barcelona.
- Increases in core property operating expenses, specifically wages, energy tariffs, building maintenance, and property insurance.
- Delivery schedules for multi-family and private residential developments that could create localized supply absorption pressures.
Figures checked by the standards desk (Paul Ostrowski): every figure in this story was matched to the source material listed below before publication.
Tally from the accuracy gate: 135 details tested, 130 found in the stored source, 5 allowed as background knowledge, nothing cut.
Sources
- Hospitality Investor - Adaptive re-use and the next phase of European urban hospitality: A Q&A with Bohopo's Minas Terlidis (October 21, 2026).
- eu.36kr - September Asia (China) Long-term Rental Apartment Development Report (October 20, 2026).
An analysis column by the Booked News desk. Every figure is taken from the sources above.
Is a figure here wrong? Say so / The corrections procedure and the log
Related stories
How property size tiers and baseline rates shape vacation rental yield
Picture from Wikimedia Commons; licence CC BY-SA 4.0; photographer Bijay Chaurasia
New York short-term rental revenue rose 361% during Harry Styles shows in March 2026
Airbnb checkout rules shift turnover costs to Canadian cottage operators
Picture from Wikimedia Commons; licence CC BY-SA 4.0; photographer Tobias Alt, Tobi 87
Short-term rental rates double in peak months as guests cap accommodation spend at $2,500
Picture from Wikimedia Commons; licence CC BY-SA 4.0; photographer DXR
Read the desk every morning.
Leave your address for the Booked News briefing: the day's figures on rates, occupancy, demand, fees, supply and returns, each with its source, in one short email.
Comment thread