Krakow and Athens led Easter 2026 short-term rental demand growth at 51%, PriceLabs said
The pricing firm reported that affordable secondary destinations outperformed major capitals, with Budapest recording a 50% surge in nights booked.
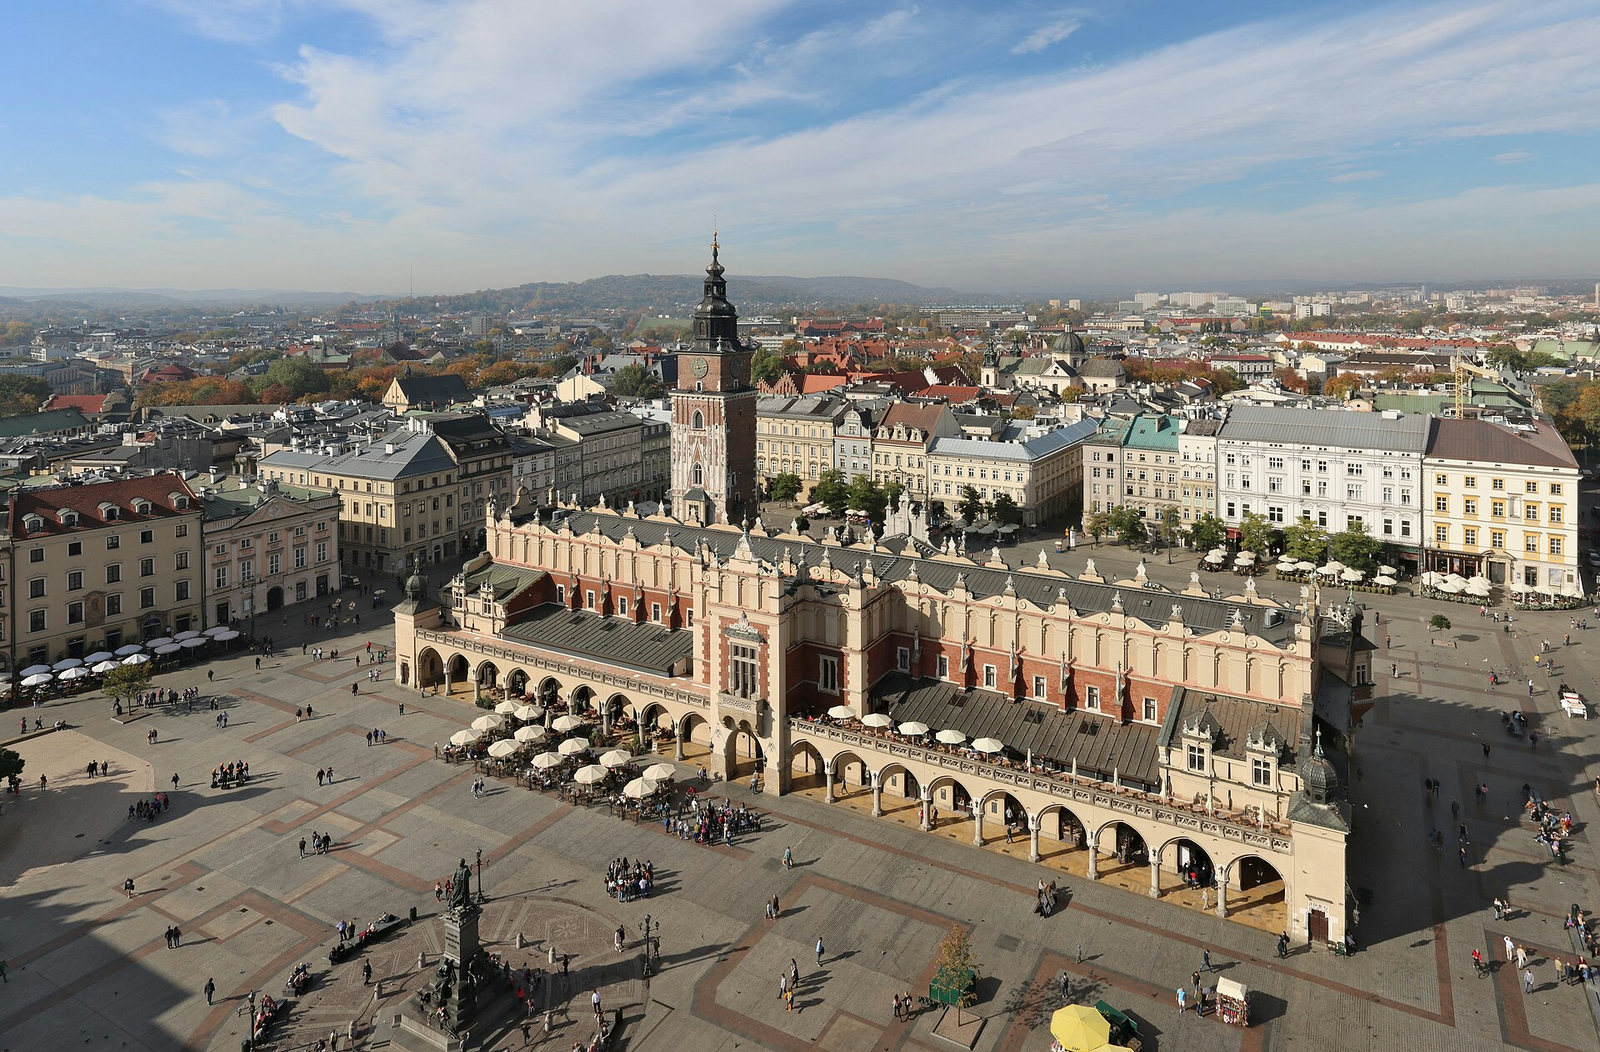
Krakow's Main Market Square, with the Cloth Hall and the Town Hall Tower. Photo: “Krakow - Cloth Hall from Basilica - 1” by Ingo Mehling, licensed CC BY-SA 4.0, via Wikimedia Commons. Resized from the original.
On March 27, 2026, PriceLabs reported that short-term rental bookings for the Easter holiday period rose 51% year-over-year in Krakow and Athens, leading a wider European travel trend where affordable secondary cities outperformed major capitals. The data, which tracked bookings across 22 European markets, revealed a structural shift in traveler behavior as guests increasingly prioritized value-driven city breaks. Rather than choosing a property first and then selecting a destination, travelers compared average daily rates across different cities before making their bookings.
This shift in consumer behavior directly benefited destinations in Eastern and Southern Europe, where nightly rates remained a fraction of those in Western European capitals. While traditional hubs like London and Paris experienced flat or declining booking volumes, secondary markets and budget-friendly cities saw substantial growth. The performance highlighted a growing divergence between markets experiencing volume-led growth and those relying on rate-led growth to maintain revenue.
What the data shows
The performance of the 22 tracked European markets during the Easter 2026 booking window showed a clear preference for affordability. Krakow and Athens recorded the highest demand growth, with both destinations experiencing a 51% rise in nights booked compared to the same period in the previous year. Budapest followed closely with a 50% increase in demand. Other secondary and Southern European markets also recorded strong double-digit growth: Málaga and Dublin both saw bookings rise 43%, Nice recorded a 41% increase, Gran Canaria rose 40%, and Seville recorded a 39% increase.
In contrast, major Western European capitals saw much lower growth or outright declines. London recorded a modest demand increase of 4%, while Paris and Bordeaux both experienced a 6% decline in nights booked. Brittany saw the largest drop in demand, with bookings falling 26% year-over-year. Cornwall also experienced a minor decline of 3%.
Despite these varying demand patterns, average daily rates rose across all 22 analyzed markets. London remained the most expensive destination with an average daily rate of EUR 428, which represented a marginal rise of 1% year-over-year. Paris recorded an average daily rate of EUR 386, representing a rise of 24% despite its 6% decline in bookings. Rome posted an average daily rate of EUR 352 alongside a 25% increase in demand. Amsterdam saw its average daily rate rise 15% to EUR 282, while bookings grew 26%.
Other markets recorded the following average daily rates and demand trends:
- Seville: average daily rate rose 19% to EUR 267, with demand up 39%.
- Edinburgh: average daily rate stood at EUR 238, with demand up 31%.
- Barcelona: average daily rate stood at EUR 234, with demand up 36%.
- Dublin: average daily rate stood at EUR 217, with demand up 43%.
- Cornwall: average daily rate stood at EUR 187, with demand down 3%.
- Prague: average daily rate rose 27% to EUR 172, with demand up 34%.
- Lisbon: average daily rate stood at EUR 154, with demand up 22%.
- Vienna: average daily rate stood at EUR 154, with demand up 23%.
- Bordeaux: average daily rate stood at EUR 145, with demand down 6%.
- Brussels: average daily rate rose 19% to EUR 138, with demand up 21%.
- Nice: average daily rate stood at EUR 134, with demand up 41%.
- Gran Canaria: average daily rate stood at EUR 134, with demand up 40%.
- Athens: average daily rate rose 9% to EUR 115, with demand up 51%.
- Brittany: average daily rate stood at EUR 107, with demand down 26%.
- Budapest: average daily rate rose 21% to EUR 100, with demand up 50%.
- Krakow: average daily rate rose 14% to EUR 98, with demand up 51%.
How it was measured
The figures were compiled by PriceLabs, a revenue management and pricing software firm. The company collected booking data from February 23 to March 10, 2026, analyzing short-term rental listings across Airbnb, Vrbo, and Booking.com. The analysis covered 22 European markets for the Easter 2026 holiday period. The metrics tracked included nights booked (representing demand) and average daily rates (ADR) compared to the same period in the previous year. The data was published on March 25, 2026, and reported on March 27, 2026.
Drivers of the value migration
The primary driver of these shifts was the visible price difference between destinations. When booking short-term rentals, travelers increasingly compared cities side-by-side on the same screen. A family searching for an Easter vacation could easily see that Krakow at EUR 98 per night or Budapest at EUR 100 per night provided cultural attractions, walkability, and restaurants at a fraction of the cost of London at EUR 428 or Paris at EUR 386. The comparison was no longer property-to-property, but rather city-to-city, and affordable destinations won that comparison decisively.
Richie Khandelwal, Co-Founder of PriceLabs, described this trend as guests widening their search beyond traditional capitals toward cities that combine good weather, cultural attractions, and more affordable accommodation. This was not a random shift in traveler interest, but rather a deliberate calculation by consumers whose budgets favored secondary and Eastern or Southern European markets. For US-based property managers, this trend mirrored the domestic primary-to-secondary market shift that reshaped short-term rental economics in the United States starting in 2022. The European data reflected the same story, occurring one cycle behind the American market.
“Demand for Easter travel remains strong across Europe, but travellers are clearly widening their search beyond traditional capitals. Cities in Eastern and Southern Europe are seeing particularly strong growth, as visitors look for destinations that combine good weather, cultural attractions and more affordable accommodation.”
The French school holiday exception
The soft demand figures in French markets—specifically Brittany falling 26%, Paris falling 6%, and Bordeaux falling 6%—were driven by local calendar mechanics rather than a structural decline in interest. In 2026, French school holidays for Zone C, which covers approximately two-thirds of the country, were scheduled to fall later than the Easter weekend.
Because domestic families are the primary demand driver for Brittany and represent a significant share of visitors to Paris and Bordeaux, they had not yet booked their Easter trips during the PriceLabs measurement window. Their holiday window fell after Easter, meaning their bookings would arrive later. The timing of school holidays in France heavily influenced domestic travel behavior and impacted early demand in these regions.
Despite the temporary drop in demand, short-term rental operators in Paris did not panic. The average daily rate in Paris rose 24% to EUR 386 per night. This demonstrated rate discipline, as managers chose to maintain their margins rather than lowering prices to chase early volume. This behavior aligned with how operators respond to regulatory and demand uncertainty across European cities that are clamping down on short-term rentals. It proved that local calendar mechanics can completely override macroeconomic demand trends, showing how market-level intelligence can prevent operators from misinterpreting raw occupancy numbers.
Volume-led versus rate-led dynamics
The PriceLabs report highlighted two distinct strategies employed by property managers across Europe: volume-led growth and rate-led growth. Understanding which dynamic applied to a specific market determined whether managers should push rates, chase volume, or defend their positions.
Volume-led growth occurred in markets where demand rose faster than supply could absorb it, pulling rates upward. In these markets, managers had significant pricing runway and could test higher rate ceilings. Examples included Budapest, where demand rose 50% and average daily rates rose 21%, and Krakow, where demand rose 51% and average daily rates rose 14%. Málaga also saw demand rise 43% alongside a 20% average daily rate increase, while Athens recorded a 51% demand increase and a 9% average daily rate rise. These markets reflected demand-supply imbalances, indicating that managers should test higher ceilings.
Rate-led growth occurred in markets where booking volumes were flat or negative, but average daily rates still climbed. This strategy relied on rate discipline, with managers choosing margin over occupancy. Paris was the prime example, where demand fell 6% but average daily rates rose 24%. This approach is effective when managers know that demand is delayed rather than absent, but it can fail if they mistake a structural decline for a temporary calendar shift.
Prague represented a unique case of dual momentum, where demand rose 34% and average daily rates rose 27% to EUR 172. This indicated that Prague was absorbing substantial new demand while simultaneously repricing upward into a new tier, reflecting genuine market heat. Conversely, London represented a mature and capped market, where demand rose 4% and average daily rates rose 1% to EUR 428, suggesting the market had reached its pricing ceiling with little room for further growth. Competition in London was described as zero-sum.
Who it affected
This shift in traveler behavior affected short-term rental hosts, professional property managers, and investors across Europe. Managers in high-priced capitals like London found themselves competing not just with neighboring properties, but with entire alternative destinations. A manager listing a property in London at EUR 428 per night was directly losing bookings to listings in Budapest at EUR 100 per night due to the visible difference in value. The competitive set had expanded, meaning single-market dashboards were no longer sufficient to explain flat booking volumes.
The data also affected how managers reacted to local market signals. A property manager in Brittany looking only at raw occupancy numbers without understanding the school holiday shift might have concluded that their market was collapsing and repriced downward. Understanding the calendar shift allowed them to hold their rates and wait for domestic bookings to arrive, avoiding an expensive pricing mistake. For hosts and managers, the Easter holidays represented a peak season that often attracted last-minute bookings and domestic visitors. PriceLabs noted that managers who kept listings up to date and optimized their profiles could succeed in attracting bookings that lasted longer than the bank holiday weekend.
What the data did not tell you
While the PriceLabs report provided detailed insights into demand and average daily rates, it did not disclose several key metrics. The data did not specify the total supply of short-term rental listings in each of the 22 markets, leaving it unclear whether demand growth was keeping pace with supply expansion. Without supply figures, it is impossible to determine the net impact on overall occupancy rates.
Additionally, the report did not provide specific occupancy rates or revenue per available room (RevPAR) for the period. It did not break down bookings by platform, meaning the relative shares of Airbnb, Vrbo, and Booking.com remained unknown. Finally, the report did not track whether last-minute bookings eventually materialized in France to offset the early declines caused by the school holiday schedule, leaving the final outcome of the Easter travel season unrecorded.
What to take from it
The Easter 2026 data shows that short-term rental competition has expanded beyond local neighborhoods to a city-to-city level. Professional managers must adapt their pricing and marketing strategies to account for broader regional trends.
- Expand your competitive set: Recognize that listings are competing with alternative destinations that offer similar appeal at lower price points.
- Analyze local calendar shifts: Before lowering rates in response to soft early demand, check local school holiday schedules and regional calendars to see if bookings are simply delayed.
- Identify the growth driver: Determine whether the local market is experiencing volume-led or rate-led growth, and adjust pricing ceilings or occupancy targets accordingly.
- Monitor cross-destination data: Use multi-market dashboards to track value migration patterns, as single-market views will not reveal why bookings are shifting to other cities.
Figures checked by the standards desk (Paul Ostrowski): every figure in this story was matched to the source material listed below before publication. The desk's review found nothing to correct.
Sources
- Rental Scale-Up (PriceLabs) - published March 27, 2026.
- India Outbound - corroborating coverage.
- BnBNews (Greece) - corroborating coverage.
Part of the Booked News record for March 2026. The desk filed this story on October 9, 2026 from a source published in the month it covers, under the same figure rule as the daily news.
Report an error in this story · Corrections policy and log
Related stories
Crete short-term rental listings fell 5.7% in June 2026 as housing prices rose
European short-term rental rates rose 8.2% in July 2026 as occupancy steadied
European short-term rental rates rose in December 2025 as Christmas market demand grew
European short-term rental supply rose 1.8% in October 2025 as demand softened
Read the desk every morning.
Leave your address for the Booked News briefing: the day's figures on rates, occupancy, demand, fees, supply and returns, each with its source, in one short email.
Comments